Category: Industry Insights

Building a Durable Software Company in the AI Era, How Embedded Payment Adds a New Dimension

By Novan Le, Head of Finance at Payabli

For most of the SaaS era, building a great software company followed a relatively understandable playbook. Find an underserved workflow, build a better product around it, establish a recurring subscription relationship, and continue adding features until the platform becomes difficult to replace. Product breadth mattered because software was expensive and slow to build. If it took a competitor several years and dozens of engineers to recreate what you had built, a strong product lead could itself become a meaningful competitive advantage.

AI is changing that equation faster than I think most of us fully appreciate.

As a finance leader, I tend to look at technology shifts through a fairly simple lens: what changes the long-term quality of a company’s revenue, margins, retention, competitive position and ultimately its enterprise value? From that perspective, the important question isn’t whether AI will create more software. It almost certainly will. The more interesting question is what kind of software will remain valuable when creating software itself becomes dramatically cheaper.

Investors and software buyers are already wrestling with that question. PwC described the software market in early 2026 as undergoing a selective repricing, with a growing distinction between durable platforms with defensible moats and products whose value resides primarily in surface-level functionality that AI can increasingly reproduce. A recent 2026 survey of more than 200 private equity investors, strategic acquirers and SaaS CEOs found that 85% viewed AI-driven commoditization as the biggest risk facing SaaS. At the same time, buyers were still willing to pay premium valuations for businesses with durable growth, strong retention, deep workflow integration and credible AI strategies.

That distinction is important. AI is not necessarily reducing the value of software. It is changing where the value resides.

From owning features to owning the workflow

One of the more useful frameworks I’ve seen recently comes from Foundation Capital’s work on what it calls “context graphs.” In a January discussion with Foundation’s Ashu Garg, Altimeter’s Jamin Ball and Animesh Koratana, the group argued that the constraint on enterprise AI increasingly isn’t model intelligence. The leading models are already sufficiently capable for many business use cases. The harder problem is giving AI the context to understand how a particular business actually operates.

Businesses make thousands of decisions that never make it cleanly into a database: why a customer received an exception, why a transaction was flagged, why one invoice was handled differently from another, which policy governed a decision, what happened afterward and whether the outcome was ultimately good or bad. Foundation calls these histories “decision traces.” Their argument is that applications sitting directly in the execution path of work have an opportunity to capture those traces and turn them into a proprietary understanding of how a business operates.

I think that concept gets much closer to what an AI-era moat actually looks like.

The traditional SaaS advantage often came from owning a system of record. The next generation of durable software will increasingly combine that system of record with a system of action. Instead of merely recording that an invoice was paid, software can determine how it should be paid, execute the payment, handle an exception and reconcile the result. Instead of simply displaying merchant risk, it can identify an anomalous pattern, determine whether the behavior falls outside policy, request additional information and route the account for review.

That matters because a product that participates in the decision and execution process sees information that a product sitting outside the workflow never sees.

Bessemer has arrived at a similar conclusion through its work on vertical AI. Its framework differentiates between AI functionality that simply improves productivity and products that own increasingly complete, high-value workflows. Bessemer specifically warns against easily commoditized capabilities such as basic extraction, matching or reconciliation in isolation. The stronger opportunity is combining AI with deeply integrated, sector-specific workflows where the application delivers economic outcomes rather than another feature.

This is also why vertical software may be particularly well positioned. A generic model can understand accounts receivable. It is much harder for a generic model to understand the complete collection workflow of a property manager, dental practice, field-service company or HOA, including the industry’s terminology, business rules, customer relationships, exceptions, payment behavior and regulatory constraints.

The vertical platform already has much of that context. The strategic question is how much more of the workflow it can own.

Why payments become more important, not less, in an AI world

This is where I believe embedded payments become particularly interesting.

Payments are sometimes discussed primarily as a monetization strategy for SaaS. That’s certainly part of the attraction, but it understates their strategic value. When payments are deeply embedded, a software company moves from helping its customer run a workflow to actually participating in the economic transaction that completes that workflow.

Consider what that means from a data and context perspective. A scheduling platform may know that an appointment was booked. A platform that also owns the payment experience can know whether the customer paid, which payment method they selected, whether the transaction succeeded, how long settlement took, whether it was refunded or disputed, and how the merchant ultimately reconciled it.

The same logic applies on the outbound side. Software may know that a vendor invoice exists, but a platform that manages payables can also see who was paid, when they were paid, which payment rail was selected, whether the payment succeeded and what happened when it didn’t.

These are not merely additional data points. They are closed-loop outcomes.

That becomes extremely valuable in an AI environment because intelligence improves when it can connect a decision to its eventual result. A system can learn that a particular risk signal preceded a chargeback, that a particular merchant onboarding pattern correlated with higher activation, that certain invoice characteristics increased the likelihood of late payment, or that vendors in a particular category were substantially more likely to accept a virtual card.

This is why I would be careful about simply calling transaction data a “data moat.” Data by itself is rarely enough. Large models are improving rapidly, third-party datasets continue to expand, and many supposed proprietary datasets turn out to be less differentiated than expected.

The more defensible asset is the combination of vertical context, workflow position, transaction history, decision-making and observable outcomes. When those components live together inside a platform, each transaction can make the system incrementally more useful.

Agentic AI makes the financial layer even more consequential

The emergence of AI agents strengthens the argument further because an agent that actually performs work eventually needs the ability to take real-world actions.

That became a recurring theme across this year’s payments and commerce conferences. In sessions featuring Amazon, AWS, Mastercard, Klarna and other software and commerce leaders, the conversation had noticeably moved past whether AI agents would participate in commerce and toward harder questions around authorization, identity, fraud, permissions and trust.

Amazon’s agentic-payments team described merchant conversations moving from “What is agentic commerce?” to “How do we get ready for it?” More importantly, merchants are beginning to ask who actually authorizes a transaction when the customer isn’t sitting in a checkout screen. AWS and other infrastructure providers separately discussed the rise of agent-to-agent commerce and the infrastructure necessary to put spending limits, authorization rules and payment credentials around autonomous software. Those same discussions noted that while consumer applications remain relatively early, B2B software use cases are already progressing toward agents operating with persistent context and delegated authority.

Mastercard made essentially the same point at its 2026 Connections conference: in a world where agents transact with other agents at machine speed, payments infrastructure has to become a layer of trust and control rather than simply a mechanism for moving money.

For vertical SaaS companies, this creates an interesting strategic advantage. The platform that already understands the customer, the workflow and the money movement is much better positioned to determine what an AI agent should be allowed to do.

Imagine a future field-service platform where an agent doesn’t simply tell a contractor that an invoice is overdue. It determines which invoices require follow-up, contacts the customer, offers an appropriate payment method, executes the payment when authorized and reconciles the result. Or a property-management platform where an agent identifies a vendor invoice, verifies the vendor, evaluates payment options, executes the payment and handles reconciliation without a person manually moving between four systems.

AI is what makes those experiences possible. Payments are what allow those experiences to finish the job.

That distinction between advising and executing may become one of the most important dividing lines in enterprise software.

The CFO case: embedded payments can change the economics of the company

There is another reason payments matter, and it is much more familiar territory for a CFO: the economics.

Traditional SaaS monetization is usually bounded in some way by subscription pricing. A business can increase prices, sell more seats, add modules or move customers into larger tiers, but monetization is still largely connected to software access.

Payments introduce a revenue stream tied to the economic activity of the customer’s business. If the customer processes more transactions, the platform has the opportunity to participate in that growth without having to acquire another customer or add another seat.

Recent platform operating data supports the significance of that model. Median payments adoption among vertical SaaS platforms increased from 27% in 2024 to 40% in 2025, while leading platforms achieved adoption rates of 80% or more. Tidemark research estimates approximately $4,200 of incremental annual recurring revenue for each customer adopting embedded payments, and the same operating data shows lower churn among platforms with embedded financial products and materially faster growth among multiproduct platforms.

What I find more interesting than the incremental revenue, however, is the second-order effect. Payments can increase revenue per customer, but they can also deepen the customer’s dependency on the platform in a constructive way. Once customers use the same system to manage the workflow, accept money, make payments, reconcile transactions and increasingly access adjacent financial products, the software becomes more central to operating their business.

That creates the potential for better retention and net revenue retention at the same time that it adds a new gross-profit stream. In financial terms, you’re improving both the quantity of monetization and the durability of the customer relationship.

That combination is important to investors because enterprise value isn’t simply a function of revenue. Buyers ultimately underwrite the durability and growth of future cash flows.

What investors and acquirers are actually looking for

There is a temptation in fintech to argue that adding payments automatically creates a valuation premium. I don’t think that’s the right way to think about it.

A poorly implemented payments business with low adoption, weak unit economics and limited strategic integration will not suddenly transform the valuation of a software company. In fact, it may create operational complexity without enough economic benefit to justify it.

Payabli’s recent roundtable discussion on how buyers evaluate vertical SaaS companies with embedded payments made this point well. The consensus was essentially that traction matters more than the story. Buyers will examine payment penetration, TPV, net take rate, cohort adoption, gross margin and the impact payments have on NRR and GRR. A company saying it has a large payments opportunity is different from a company demonstrating that its customers have adopted payments and that the resulting revenue behaves predictably over time.

That view is consistent with the broader M&A market.

·  Kroll’s 2026 software M&A analysis found strategic buyers accounting for 76% of transactions in the period it analyzed, with buyers particularly focused on AI capabilities, data infrastructure and workflow automation. SEG similarly describes buyers becoming more selective about targets while concentrating competition around companies with strong retention, durable revenue and clear competitive positioning.

·  PwC uses a term I like for this: workflow gravity. The most defensible software has enough domain expertise, proprietary context and ecosystem entrenchment that AI makes the platform more valuable rather than easier to replace.

·  Embedded payments can contribute to that gravity because payments touch the customer’s workflow, data, economics and operating processes simultaneously.

·  A June 2026 discussion between L.E.K., CFO Dive and Worldpay went even further. Their research found valuation premiums as software platforms progressed from software-only businesses into embedded payments and then broader embedded finance. Their illustrative model suggested embedded payments could contribute meaningfully to enterprise value over a five-year investment period. I would treat any exact modeled uplift as scenario-specific rather than a universal rule, but the underlying mechanism is compelling: payments add recurring transaction economics, deepen financial workflows and create logical pathways into products such as payables, working capital and other embedded financial services.

·  The strategic ceiling of the software company gets higher.

The opportunity isn’t to become a payments company

None of this means every vertical software company should build payment infrastructure itself.In fact, I think the opposite is usually true. Payments contain an enormous amount of complexity that end users rarely see: merchant underwriting, card-network requirements, risk monitoring, tokenization, compliance, settlement, reconciliation, pricing, disputes, money movement and support. The more deeply payments become embedded into a platform, the more operational infrastructure exists beneath the surface.

The software company’s scarce resources are usually better spent on the things that are unique to its market: understanding the vertical, controlling the customer experience, designing the workflow and building the intelligence that makes that workflow better.

The role of an infrastructure partner should be to make the underlying financial layer possible without forcing the software company to recreate a payments organization from scratch.

That is the philosophy behind what we’re building at Payabli. Payabli gives software platforms infrastructure across Pay In, Pay Out and Pay Ops so they can own the embedded financial experience and participate in its economics while we handle much of the complexity underneath it. Increasingly, that infrastructure is intelligent as well. Amigo and Payabli’s broader intelligence platform bring AI into onboarding, payments analytics, risk, vendor enablement and other operational workflows, while agent-facing tools are being built to allow software agents to query, authorize, reconcile and ultimately execute payments natively.

I think this architecture is particularly relevant to the AI era. A vertical software company should not have to choose between becoming an AI company and becoming a fintech company. It should be able to use AI to make its vertical workflow more intelligent while using financial infrastructure to make that workflow economically complete.

Building for enterprise value in the next generation of software

We’re still early enough in the AI transition that anyone claiming to know exactly how software businesses will be valued five or ten years from now is probably overconfident. Even today, investors disagree about which application-layer moats will persist, how quickly agents will replace traditional interfaces, and whether many current software categories expand or collapse. But the market is already giving us useful signals.

The cost of creating functionality is falling. Buyers are becoming more skeptical of products differentiated primarily by features. At the same time, they continue to place significant value on companies with durable revenue, embedded workflows, proprietary context, customer trust and clear economic value.

That suggests that the best response to AI isn’t simply to ship more AI features.

For vertical software companies, the more durable strategy is to move deeper into the customer’s business: own more of the workflow, participate in more of the actions, understand more of the context and connect those actions to measurable outcomes.

Embedded payments can be an unusually powerful part of that strategy. Done well, payments add gross profit and expansion revenue, create a more integrated customer relationship, produce high-value transaction and outcome data, open the door to broader embedded finance, and provide the trusted execution infrastructure that increasingly autonomous software will require.

The software companies that are most interesting to me aren’t becoming less important because of AI. They’re becoming more deeply embedded in how their customers actually operate.

And when the software owns both the workflow and the movement of money through it, AI doesn’t have to erode the moat. It can make the moat deeper.
From Vertical SaaS to Vertical AI: How to turn your product into a payments driven revenue engine.

Guest Post by Ershad Jamil | Former CGO, ServiceTitan

AI Shouldn’t Just Automate Work. It Should Help Businesses Get Paid.


Vertical SaaS companies were built to meet the discreet operational, workflow, and regulatory needs of a specific industry, like healthcare or construction. With the rise of embedded payments, these software companies soon became payments platforms.  Now, the question for Vertical SaaS platforms is how to leverage AI to help your customers become payments driven revenue engines. 

While AI and automation can significantly improve industry-specific work deliverables – from scheduling appointments to generating industry-formatted proposals, those applications focus on reducing administrative overhead or simplifying workflows. What would be even more valuable? Expediting how quickly a business gets paid. That’s where the Vertical SaaS companies will become Vertical AI companies and truly differentiate themselves. 

For years, software platforms have treated payments as the final step in a workflow. The job gets completed, an invoice gets generated, and eventually someone gets paid. AI gives us an opportunity to rethink that sequence. Instead of viewing payments as something that happens after the workflow, they should become part of the workflow itself. The next generation of Vertical AI companies won’t simply automate operations. They’ll help customers get paid faster—and in doing so, create entirely new revenue opportunities for themselves.

Every AI Workflow Should End With a Payment

No matter the industry, most service businesses follow a remarkably similar customer journey. A customer requests a service. A quote is generated. An appointment is scheduled. The work gets completed. An invoice is created. Payment is collected.

Today’s AI products are becoming incredibly effective at improving nearly every operational  step leading up to payment. AI can answer inbound calls, qualify prospects, recommend pricing, schedule technicians, summarize job notes, generate estimates, and even draft invoices. But in many cases, once the invoice is generated, the workflow simply stops.

(I’ve written before about how this gap between operational and financial workflows slows down cash flow.)

Imagine an AI sales agent preparing a quote for a homeowner. Instead of emailing a proposal and waiting for a response, the AI presents financing options, answers questions, and captures a deposit the moment the customer approves the estimate. Or imagine an AI scheduling assistant booking a service appointment. Before confirming the visit, it automatically secures the required deposit, reducing cancellations while improving cash flow. After the work is complete, the AI reviews technician notes, generates an invoice, explains the charges, answers customer questions, and securely collects payment before the conversation even ends.

In each case, AI isn’t replacing the payment infrastructure. It’s eliminating the friction that normally exists before the payment occurs. The faster businesses convert completed work into collected cash, the healthier those businesses become.

Better Customer Outcomes Create Better Platform Economics

This shift has implications that extend well beyond customer experience. Historically, software companies monetized subscriptions. In the past 10+ years, vertical SaaS companies embedded payments and began participating in payment volume generated on their platforms. As Brad Weekes of Software Equity Group says, “If you give me a pure SaaS company versus a SaaS plus payments company with the same strong financial metrics, I’m all over it.” Vertical AI companies have an opportunity to take that model one step further.

Every time AI helps a customer close another job, capture another deposit, recover another payment, or reduce the time it takes to collect an invoice, the software platform creates measurable economic value for its customer. If payments are embedded directly into those AI-driven workflows, the platform benefits alongside its customers.

Revenue becomes directly aligned with customer success. As customers process more payments, collect cash faster, and improve their businesses, the software platform grows with them. That’s a fundamentally different business model than simply charging another monthly subscription. You’re no longer monetizing software usage—you’re participating in customer outcomes.

The Next Generation of Vertical AI Platforms

Over the next several years, I believe we’ll see a growing number of AI-native software companies build products that don’t stop once work has been completed. They’ll own the entire lifecycle—from customer acquisition and quoting to scheduling, payment collection, reconciliation, and financial operations.

The most valuable AI won’t simply answer questions or automate administrative work. It will help businesses improve cash flow, accelerate collections, and generate more revenue.

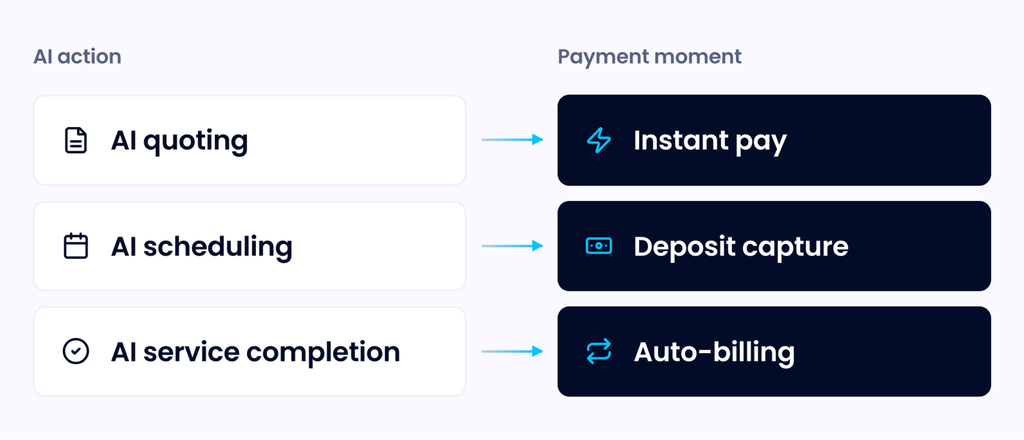
Here’s a view of how AI will change the revenue collection workflows for Vertical AI companies:

  • AI quoting → instant pay
  • AI scheduling → deposit capture
  • AI service completion → auto-billing

As founders think about building the next generation of vertical AI companies, payments should no longer be viewed as a separate feature that’s added later. They should be considered part of the product from day one. Payments become the mechanism that converts AI-driven activity into measurable business outcomes.

None of this is easy to build. Embedding deposits, invoicing, financing, and reconciliation directly into an AI agent’s conversation requires real financial infrastructure — money movement, compliance, reconciliation — sitting underneath the product, not bolted on top of it. 

That’s the layer companies like Payabli exist to provide: Pay In, Pay Out, and financial operations built to be embedded into AI-native experiences from day one, so platforms can focus on the workflow instead of rebuilding payments from scratch. Get that infrastructure right, and the result isn’t just better software — it’s a platform that helps customers complete more work, collect more revenue, and improve cash flow, while creating a powerful new monetization engine for the software company itself.

The next generation of Vertical AI companies won’t simply automate business workflows. They’ll automate business outcomes.

How AI-Powered Customer Experience Gets You Paid Faster

Guest Post by Ershad Jamil | Former CGO, ServiceTitan

Most payment problems aren’t payment problems. They’re customer experience problems.

Businesses don’t usually struggle because customers are unable to pay. They struggle because customers don’t pay immediately. Invoices get buried. Payment links are hard to find. Questions go unanswered. And collections teams spend days chasing customers who were ready to pay the moment they got a clear answer.

Having launched payments businesses at ServiceTitan, BuildOps, Otter, and several other vertical software companies, I’ve seen this pattern repeat across every industry. The bottleneck is almost never the payments infrastructure. It’s the customer experience that sits in front of the payment.

The Gap Between Customer Communication and Payment Collection

Traditionally, customer communication and payment collection have existed as separate workflows. A customer receives an invoice, ignores it, receives a reminder, has a question, waits for an answer, and eventually makes a payment. Multiple systems, departments, and interactions are often involved before money is collected. The result is a poor experience for both the business and the customer.

Businesses want to get paid faster. Customers want quick answers and an easy way to complete transactions. Yet many organizations still force customers to leave a conversation, search for a payment portal, navigate multiple screens, or wait for a response before they can pay. In fact, 42% of businesses cite the lack of supplier or customer portals as a significant payments challenge. (PYMNTS). The longer the journey, the lower the conversion rate and the slower the collection cycle.

One lesson I’ve seen repeatedly across vertical SaaS is that the most successful payments businesses don’t simply process transactions. They remove friction. The reason products like ServiceTitan Payments, BuildOps Payments, Toast Payments, Shopify Payments, and others have been successful isn’t because they move money differently. It’s because they make paying dramatically easier. The best payment experience is one where the customer barely has to think about the payment experience at all.

AI Is Bringing Customer Experience and Payments Together

AI-powered chat and voice agents are beginning to eliminate the gap between customer communication and payment collection. Instead of sending an invoice and hoping for a response, businesses can now engage customers in real time. An AI agent can proactively reach out, answer questions, explain charges, resolve concerns, and provide a payment link within the same interaction.

Imagine receiving a text message that says, “Your invoice is ready. Would you like to pay now?” 

The customer asks a question about a charge on the invoice. The AI agent explains the service performed, answers follow-up questions, and instantly presents a secure payment option. The payment is completed without the customer ever leaving the conversation. What previously required multiple emails, phone calls, reminders, and follow-ups can now happen in a matter of minutes. The payment itself hasn’t fundamentally changed. The customer experience has.

Embedded Payments Become More Powerful Inside Conversations

Embedded payments have already transformed how software platforms monetize transactions. The next evolution is embedding payments directly inside customer interactions. Whether through SMS, web chat, voice conversations, customer portals, or AI agents, payments can become a natural extension of the conversation itself. The goal is no longer simply to process payments efficiently. The goal is to remove every unnecessary step between customer intent and completed payment.

When customers can ask questions, receive answers, and complete a payment without switching channels or navigating additional workflows, collection rates improve, payment timing accelerates, and businesses get access to cash faster. The fewer clicks, redirects, and delays involved, the higher the conversion rate and the faster the business gets paid.

The Future of Payments Is Faster Cash Flow

For the last decade, the payments industry has focused on optimizing payment processing. The next decade will be about optimizing payment collection.

The companies that win won’t simply build better payment infrastructure. They’ll build better payment experiences. They’ll recognize that every payment is part of a customer journey: reducing friction, answering questions instantly, and making it effortless for customers to complete a transaction the moment they’re ready.

In that world, customer experience becomes a revenue driver. Better experiences lead to faster collections, lower operational costs, higher customer satisfaction, and healthier cash flow. The future of payments isn’t just fintech, it’s the convergence of AI, customer experience, and payments into a single, frictionless workflow.

So what should businesses expect from the next generation of embedded payments platforms?

They should look for partners that provide:

  • An AI agent trained on your business that can answer customer questions about invoices, estimates, balances, financing, and payment options in real time.
  • Multi-channel engagement across SMS, email, web chat, voice, and customer portals—meeting customers where they already communicate.
  • Embedded payments inside the conversation, allowing customers to review, approve, finance, and pay without leaving the workflow.
  • Deep integration with your vertical SaaS, ERP, CRM, accounting, and field service systems so every interaction has context.
  • Automated collections and follow-up, using AI to remind customers, resolve objections, and reduce days sales outstanding (DSO).
  • Actionable insights into payment bottlenecks, customer behavior, and collection performance to continuously improve cash flow.

The companies that embrace this shift will discover a simple truth: Better CX → Faster Cash.

Designing Payments That Disappear

By Lau Linares, Lead Product Designer at Payabli

Picture this. You are at the store with a cart full of groceries, paying from the store’s own app, steering the cart with one hand and scanning items with the other. The checkout process is going smoothly: tap, tap, tap, payment method selected, card already on file. Then you notice the CVV field sitting empty and waiting for manual input. Damn!

So now, in the middle of a flow that was supposed to take seconds, you have to pull your cart to the corner, dig through your purse, and find the physical card you only hopefully remembered to bring. An experience that felt effortless a second ago has quietly fallen apart in your hands.

That single moment is what I want to talk about. The best payment experience is the one you never notice, and most of the time the reason we do notice is that something asked us to work harder than we should have, or honestly, harder than we want to (human laziness is a real thing).

What “disappearing” actually means

When I say a payment should disappear, I am not talking about hiding it or rushing it. I am talking about a flow that is fully there and working while the person using it barely feels its weight, with no friction, no broken steps, and none of that sinking “wait, do I really have to enter all of this again?” that turns a quick task into a chore.

Paying should feel like a single tap. Once you have lived inside something like Apple Pay or Tap to Pay, the traditional payment form starts to feel like a relic from another era. That is exactly why, at Payabli, the team has been building Tap to Pay into a dedicated SDK, one that turns an NFC-enabled iPhone into a payment terminal with no extra reader, no dongle, and no hardware at all, embedded directly inside our partners’ own apps. Working alongside engineering on it has only made me more convinced of the point: the bar today is the quiet absence of that long form asking for your full name, your card number, your CVV, and your zip code one more time, as if you had never been here before.

Everything I believe about this comes down to one idea that is almost embarrassingly simple: set and forget. A platform worth trusting should remember you.

The form is only the surface

Payment flows are one of the most used patterns in the entire world, and they are also, somehow, one of the most confusing. Even when every product is asking for the same handful of things, each one asks in a completely different way, stretching across one step or five, scattering buttons wherever they happen to fit, and rarely telling the user what comes next or why a particular field is even there. The styling changes from product to product while the underlying experience gets quietly ignored.

This is where I see platforms fool themselves, convinced they have modernized payments because they added a saved card or a shinier button. But storing a card and actually delivering ‘set and forget’ are two very different things. A flow that keeps your card on file yet still demands the CVV on every single purchase, exactly like my grocery story, has done the technical work while letting the design betray the person it was supposed to serve.

A lot of what passes for modern payment UI is really just a prettier version of the same form, dressed up with new colors and rounded corners while keeping the same four fields underneath. The question worth asking was never how to style the form, but whether the form needed to be there at all.

Trust is earned across the whole relationship

Here is the part that tends to get skipped: invisibility only works once trust has already been built. The flows that feel like magic feel that way precisely because the company behind them earned that credential long before you reached the checkout. A platform that has not yet earned the same trust cannot simply borrow the button and expect the feeling to come along with it.

And trust reveals itself most clearly at the scariest moment of any flow, the second right after you hit pay. What is actually running through someone’s mind is fear in its plainest form: where did my money go, am I about to be charged twice, do I need to wait, what just happened?

When you press “Pay” and the screen answers with “Something went wrong” instead of a clear, calm confirmation, the spell breaks and the trust goes with it. That is why designing payments has so little to do with the form itself, and so much to do with whether the platform is reliable enough that the fear never has a chance to surface.

What I want our designers to carry with them

Confidence was never something you build by adding steps. It grows out of the boring and invisible work of storing the right data, remembering the user, and confirming clearly and immediately that the money moved. Get that right, and the payment disappears in the best possible way.

So my take, as the designer behind a lot of these flows, is to stop polishing the form and start questioning it. Kill every moment where we ask people to re-prove something they already handed us, and treat returning users like we actually know them, because we do.

The magic was never the button. The magic is the moment someone taps “Pay” and feels absolutely nothing, because somewhere along the way they stopped worrying and simply trusted that it would work.

Gracias por el cafecito. Now go delete a form field.

How Strategic Buyers Evaluate Your Embedded Payments

In our last article, we explored why payments matter when it comes to your company valuation.  Now we’re going to dig into the details about how strategic buyers will evaluate your embedded payments.  We’ll cover the baseline and standout metrics they want to see and how you should plan your embedded fintech approach to meet those expectations.

Invest in your payments proof points

“It’s a lot easier to sell a payments story when there’s actual revenue. Buyers want proof points—not just a narrative.”

You need to demonstrate that payments is not just a capability, but a proven monetization stream.  What this means is showcasing real adoption within the install base and increasing penetration over time.

Real adoption means tracking payment volume over time.  Showcase how it is trending.  Dig into the cohorts over time.  

Stop measuring payment penetration as a snapshot. Start measuring it as a cohort.

Most platforms look at payment penetration today and call it a day. But that number tells you almost nothing on its own. The real question is: what did your cohort from three years ago look like when they signed on, and how has that group grown since?

Cohort analysis shifts the conversation from “where are we now” to “are we actually getting better at this.” Are onboarding improvements moving the needle? Is a new pricing model driving faster adoption? Are targeted campaigns pulling more volume through the platform over time?

Track penetration by cohort, and you stop guessing. You start seeing exactly which levers work, and which ones are just noise.

Download the Payments Cohort Analysis Template →

Finally, you need to own your metrics up and down the P&L. It’s not only about total payment volume and penetration rate, it’s knowing your net take rate. You need to demonstrate real ownership over the net revenue line item.

Your Best-in-Class Payments & SaaS Structure

If you’re still debating how to structure your payments into your Vertical SaaS foundation, Brad is certain there’s a winning structure.  You want to showcase both predictable revenue and a growth upside.  That’s why this model wins:

  • Strong SaaS foundation 
  • Payments revenue layered on top

“SaaS sells seats and workflows—but payments monetizes activity. The customer can grow, and you’re doing nothing, and still generating more revenue.”

This approach de-risks revenue, enhances valuation clarity, and it balances stability and expansion.  It shows the most holistic view of your business.   

If you’re an earlier stage company, you’ll require a heavier SaaS base.  As you scale, you’ll likely need to meet a minimum SaaS floor to ensure buyer confidence.  At this stage, you should be working towards a 50/50 revenue split between recurring SaaS and transactional payments.  As you continue to grow, buyers are likely going to put an even higher value on payments revenue.  As Brad explains, “We try to make the argument that payments revenue can actually be more valuable than contracted SaaS—because it grows with customer activity.”

Characteristics of Top-Performing Embedded Payments Companies

Brad has seen a range of companies come through the pipeline over ten years at Software Equity Group and knows what good looks like. 

“The perfect company is one that’s had payments revenue for three or four years, where you can see a steady cohort of growth and consistency, and improved retention over time.”

Here’s what the top-performing companies all bring to the table:

  • 3–4+ years of payments history
  • Consistent cohort growth
  • High payment penetration
  • Strong retention metrics
  • Payments deeply embedded in workflows
  • A Strong Financial Profile:
    • Strong Rule of 40
    • High gross margins
    • Efficient growth (balanced burn)

If you meet these performance standards, you’ll earn strong interest from private equity groups.  You’ll also be likely to have more competitive deal dynamics and reach your premium valuation potential. 

“If you give me a pure SaaS company versus a SaaS plus payments company with those characteristics—I’m all over it. I know I can get the PE market really excited.”

Why Vertical SaaS Founders Should Act Now

Embedded fintech is becoming a standard, even an expectation, for vertical SaaS companies. 

Keep in mind that mission-critical products will always command higher multiples.  There is power in niche markets as well – as long as your product is a “must-have” not a “nice-to-have.” There’s a great opportunity in being number one in a small TAM.  With niche dominance and payments, you’ll have strong defensibility.

 Brad sees a number of high-value verticals on the horizon, including:

  • Real estate
  • Healthcare
  • Government
  • Manufacturing
  • EdTech

As the market continues to emphasize efficiency and monetization, keep these elements in mind as you build your embedded payments offerings and plan your exit strategy:

  • Traction beats vision when it comes to valuation
  • Deep integration beats surface-level add-ons
  • The best financial model combines SaaS stability and payments upside

By following this guidance, you’ll build a stronger business and create a more compelling exit story.

Payabli can be your partner to accelerate faster time to market, improve monetization and ensure a scalable embedded payments infrastructure.  Schedule a demo with our payments experts today.

Embedded Payments Is a Product, Not a Feature

By Sierra Kotwicki | Product Marketer at Payabli

What a product marketer sees when a platform treats payments like a checkbox.


I market products for a living. When I joined Payabli as its first dedicated product marketer, my whole job became understanding who payments is for, what job it does for them, and how to say it so the right people actually care.

Which means I notice when something that should get that treatment doesn’t. In vertical SaaS, that something is almost always payments.

Most platforms don’t market payments. They just switch it on. It shows up as a toggle in account settings, a line on the pricing page, a “yes, we do that” in an RFP – and then everyone moves on. The work that any other product would get – figuring out who it’s for, what it does for them, how to launch it, how to prove it – never happens.

Here’s the distinction I keep coming back to. A feature is something you switch on. A product is something you do the work to understand, position, launch, and prove. And the product go-to-market work is the part I see most vertical SaaS platforms skip, because payments technically function the moment it’s enabled. It processes. A transaction goes through. It looks done. So nobody does the marketing – and then everyone wonders why merchants aren’t adopting.

Let me walk through the work that gets skipped. It’s all product marketing, and none of it is glamorous.

“Merchants” is not an audience

Once payments go live, most vertical SaaS platforms promote payments as a feature with a general announcement: “Payments are now available!” – sent to their entire merchant portfolio, identical copy, one and done.

But your merchants aren’t one audience. A solo practitioner who runs their whole business from their phone has nothing in common with a multi-location operator with a back-office team, except that they both pay you. They have different fears about payments, different reasons to adopt, different things that make them hesitate. A product marketer’s first move is to segment – to figure out which merchants have the most to gain and what specifically would move them – and then convey the different value propositions to each.

One generic blast isn’t a launch. It’s a notification. And notifications don’t change behavior.

Nobody wakes up wanting payments

This is the one I’d tattoo on every platform team if I could.

Merchants do not want payments. They want to get paid without chasing an invoice for three weeks. They want to stop reconciling two systems by hand every week. They want to stop losing a sale because the only option was “mail us a check.” Those are the things they want. Payments is just the mechanism.

Feature-thinking markets the mechanism: “We support ACH, cards, and digital wallets.” So what? Good product marketing markets the job that gets done: “Get paid the day you finish the work, not the month after.” Same capability – but one is a spec sheet and the other is a reason to care. The discipline here is brutally simple and almost nobody does it: take every payments feature you’ve got and run it through the “so what?” test until you reach something a merchant would actually feel.

Switching it on isn’t a launch

In a feature mindset, the moment the code ships, the job is done. In a product mindset, that moment is the starting line.

Adoption is its own motion, and a lot of it is product marketing: the in-product nudge at the moment a merchant would feel the pain, the activation sequence that walks them from “enabled” to “first transaction,” the milestone messaging when they hit their tenth payout. A product gets an adoption plan. A feature gets a changelog entry and a shrug.

And here’s the part feature-thinkers never get to: once you’re marketing adoption, you can actually measure which message works. Which value prop drives activation? Which segment converts? That’s message-market fit, and you only get to learn it if you treat the launch as something to market in the first place.

Your own team is your first market

Before a single merchant hears about payments, your own people have to be able to talk about it. Your CSMs, your support team, your account managers – if they can’t explain in one sentence why a merchant should turn payments on, no merchant ever will.

Payments adoption dies internally first. This is why internal enablement is product marketing, not an afterthought to it. Someone has to arm the people closest to the merchant. Otherwise the best positioning in the world never leaves the building.

Claims don’t travel without proof

The last thing a feature never gets, and a product always needs: proof. A platform will say “merchants love our payments” with nothing behind it. A product marketer’s instinct is to ask how do we know, and can we show it. Proof is what makes a claim portable. Without it, your messaging is just an assertion competing with everyone else’s assertions.

For what it’s worth, the proof we lean on at Payabli is scale: hundreds of billions of dollars moving across more than 100 vertical platforms. But the number only matters because we can point to what it did for the platforms behind it. A statistic with no story is just a feature in disguise.

The takeaway

Treating payments as a product isn’t about charging more for it. It’s about doing the work – knowing who it’s for, naming the job it does, marketing the launch instead of just shipping it, beating the status quo, arming your own team, and bringing proof.

That work is product marketing. It’s unglamorous, it’s mostly invisible when it’s done well, and it is the entire difference between payments that sit in a settings menu and payments your merchants actually adopt.

If you’re reading this thinking “we switched payments on a year ago and never really marketed it” – that’s not a problem, that’s the opportunity. Let’s have a conversation.

Hosted vs. Embedded vs. API: Which Payments Model Fits Your SaaS Platform?

When it comes to embedded payments, one size never fits all. Every vertical SaaS platform has different technical capabilities, operational resources, growth timelines, and revenue goals. That’s why Payabli built our partnership approach around a single commitment: meeting you exactly where you are and growing with you from there.

Whether you’re launching your first payment feature or operating a full-stack payments business, Payabli gives you three paths to embedded payments – and the freedom to mix and match across all of them.

Embedded Payments Infrastructure Built for Where You Are – and Where You’re Going

Payabli’s embedded payments infrastructure is designed around how vertical SaaS platforms actually grow – not how a rigid vendor wants you to buy. You choose how you start, how deep you go, and how fast you move. And no matter which path you’re on, Payabli’s white-label solutions keep your brand front and center, so payments always feel native to your product.

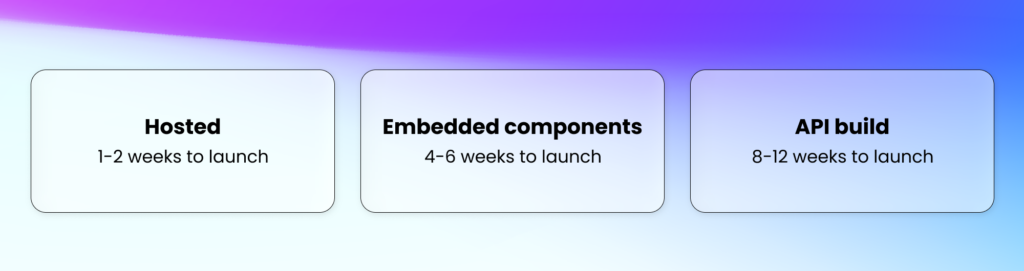
1. Hosted Solution: Launch in 1-2 Weeks with Minimal Lift

The goal: Go live fast with zero dev work and immediate revenue.

This is the fastest path to embedded payments – little to no engineering sprint required. With Payabli’s hosted solution, your customers click “pay,” land on a hosted payment page, and return to your platform. Simple, proven, live this month.

With Payabli, you can go live using:

  • Pre-built, hosted payment and onboarding forms that require minimal developer effort
  • White-label experience that keeps your brand front and center
  • Payabli-managed operations, including underwriting, onboarding, risk, and support – including end-to-end merchant support, so your team stays focused on your core product, not payment tickets
  • Start making money on payments immediately

You don’t need a payments team or a deep technical build. Plug in, go live, and start generating revenue while validating product-market fit.

Built for: Early-stage SaaS platforms, lean engineering teams, or any platform that wants to prove the payments opportunity before committing to deeper integration.

2. Embedded Components: Go Deeper & Gain Independence in 4-6 Weeks

The goal: Payments that live inside your platform – faster than a full custom build. Begin to take on more operational ownership at your own pace.

Once you’ve validated demand and built confidence in operating payments, embeddable components enable you to embed Payabli’s capabilities more deeply into your platform – making payments feel truly native to your product.

What this enables:

  • Payment widget, reporting, and boarding – easily enabled via no-code or low-code embedded components
  • Looks and behaves like you built it from scratch
  • Mix managed and self-service operations, handling some functions yourself while Payabli supports others
  • Tailor workflows around your industry’s specific needs
  • Enable more advanced features like custom pricing models, enhanced reporting, or additional payment methods

You get the native feel of a custom build at a fraction of the time and effort – a sweet spot between speed and sophistication.

Built for: Scaling SaaS platforms ready to differentiate their payments experience and develop operational muscle.

3. API Build: Full Control in 8-12 Weeks

The goal: Build the exact payment experience you want, with complete control over every detail.

For platforms ready to operate like a sophisticated payments business, Payabli’s API-first infrastructure gives you everything you need to run a full-stack payments operation. Every touchpoint, exactly as you designed it. 

What’s included:

  • Set and manage your own underwriting criteria
  • Operate your own risk program with granular controls
  • Build fully custom onboarding and servicing workflows
  • Own pricing, economics, and merchant lifecycle management
  • Automate end-to-end operations with deep technical integrations
  • Deliver a fully white-labeled payments experience from start to finish

You’re not just offering payments – you’re running a PayFac-level operation that drives significant value for your platform and your customers.

Built for: Mature SaaS platforms with dedicated payments teams treating payments as a strategic revenue driver.

The Real Differentiator: Mix, Match, and Scale

What makes Payabli unique isn’t any prescribed sequence – it’s that you can move fluidly between them, mix capabilities across them, and shift your approach as your business evolves. No rigid tiers. No outgrowing your provider.

With Payabli, you can:

  • Move at whatever pace makes sense for your platform
  • Mix and match capabilities – start with hosted, layer in embedded components, graduate to API when you’re ready
  • Shift operational responsibilities to your team or back to Payabli as your needs change
  • Choose your customer support model – let Payabli handle merchant support communications end-to-end while you own the merchant communication directly, or operate like a PayFac with Payabli behind the scenes while you own the merchant relationship directly
  • Scale without ever needing to re-platform

As Aaron Vela, Payabli’s Account Executive, puts it: “We align with you on service, operations, and technology all along the way. Whether you want to start small and scale gradually, or move quickly with advanced capabilities, our platform and team are designed to meet you exactly where you are.”

That flexibility isn’t a feature – it’s the foundation.

Why This Matters for Vertical SaaS: The Payments Platform You’ll Never Outgrow

Most payment infrastructure providers force a choice: oversimplified tools that cap your potential, or complex enterprise platforms that demand massive upfront resources. With With Payabli, you don’t have to choose – and more importantly, you never have to choose again.

There’s no ceiling on what you can build. No exit ramp that forces a costly re-platform when you scale. No tier upgrade that holds your next feature hostage. You launch at whatever stage makes sense for your business today, and the infrastructure grows with you.

You can:

  • Launch quickly without sacrificing future sophistication
  • Prove the payments opportunity before committing significant resources
  • Scale your investment in payments alongside your platform’s growth
  • Maintain full optionality to shift your approach as your business evolves
  • Never outgrow your provider – Payabli grows with you from day one

What the Vertical SaaS Journey Often Looks Like

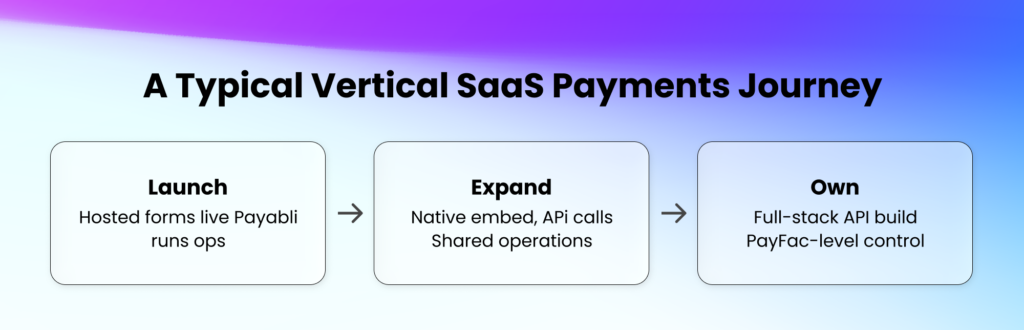
Every SaaS platform is different, but here’s a common progression to revenue generation:

Months 1–6: Go live with hosted onboarding and payment forms. Payabli manages underwriting, support, and risk. You prove that customers want embedded payments and early revenue starts flowing.

Months 6–12: Integrate via API for deeper customization. Embed more workflows natively. Take on select operational tasks. Adopt new tender types, pricing models, or reporting tools.

Months 12+: Own risk, underwriting, and pricing end-to-end. Build tailored experiences for different merchant segments. Scale with fully automated workflows. Operate a full-stack payments business powered by Payabli’s APIs.

The pace and path are always yours to define. When the infrastructure doesn’t hold you back, there’s no limit to how fast you can grow:

“With Payabli’s simple APIs and Pay Out capabilities, we launched a payment solution for our end clients in record time, enabling us to facilitate millions of dollars in payments each month. Bringing an Accounts Payable product online has transformed our business — expanding into new markets, evolving into a fintech leader, and achieving more payment volume this year than all of last year combined.” – Aditya Kaddu, CEO and Founder at EdStruments

Ready to Start?

You don’t need a fully formed payments strategy to begin working with Payabli. You just need to take the first step. Whether you want to launch fast, go deep, or take full control (or start somewhere in between) – Payabli has the infrastructure, partnership, and flexibility to meet you there.

Schedule a demo and let’s talk about where you are today, and where you want to go on your embedded payments journey.

Why Embedded Finance Is No Longer Optional in the AI Era

Guest Post by Ershad Jamil | Former CGO, ServiceTitan

Key takeaways

  • As AI makes software features easy to copy, embedded finance is the most durable layer vertical SaaS can own, because it ties your revenue to your customers’ transactions, not to whether they renew.
  • 88% of organizations now use AI, so a feature-only moat no longer holds.
  • Embedded payments grow your revenue as your customers grow and make your platform far harder to leave.
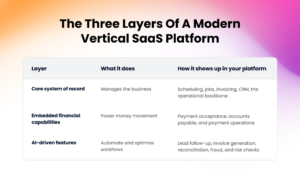
  • The strongest platforms own three layers: a system of record, embedded finance (payment acceptance, accounts payable, and payment operations), and AI-driven workflows.

For the better part of the last decade, vertical software companies operated on a relatively simple and highly effective model: build a great product, charge a monthly subscription, and scale recurring revenue. It was clean, predictable, and, for many, incredibly successful.

But that model is starting to show cracks, and AI is accelerating the shift.

Why is subscription-only SaaS losing its edge in the age of AI?

We’re entering a world where software features are easier to build, faster to replicate, and increasingly commoditized. What once required years of engineering investment can now be developed in a fraction of the time. As that happens, the durability of pure subscription revenue comes into question. If your differentiation is primarily feature-based, it’s becoming harder to defend over time.

The pressure is not theoretical. AI use inside organizations climbed from 78% to 88% in a single year, and as those capabilities spread, the features that once set a platform apart get matched far sooner. 

That doesn’t mean SaaS is going away. It means it’s no longer enough on its own.

How did embedded finance go from optional to essential?

Long before the current wave of AI, there was an emerging idea that many software companies initially resisted: embedding financial technology directly into their platforms.

A decade ago, this felt like a departure from the core SaaS playbook. Payments, in particular, introduced a very different monetization model. Instead of charging a fixed monthly fee, revenue became tied to customer outcomes. You made money when your customers processed transactions, when they got paid.

For founders used to predictable subscription revenue, that felt uncertain. It introduced complexity around compliance, underwriting, and operations. It wasn’t obvious that the tradeoff was worth it.

But over time, something important became clear. Software that helps businesses operate is valuable. Software that helps businesses make money and manage money is indispensable.

What turns a software feature into financial infrastructure?

Today, embedded FinTech is no longer a “nice to have.” It has become one of the most powerful levers for growth and retention in vertical software. When you enable a customer to accept payments, pay vendors, manage cash flow, and reconcile transactions directly within your platform, you move from being a tool to becoming part of their financial infrastructure. That shift changes everything.

Revenue becomes more aligned with your customer’s success. As they grow, you grow. As they process more transactions, your monetization expands naturally. Just as importantly, your product becomes significantly harder to replace. Financial workflows are deeply embedded, and once they’re integrated into daily operations, switching costs increase dramatically. This is why so many of the most successful vertical SaaS companies today are also, in many ways, financial platforms.

Does AI replace embedded finance, or amplify it?

There’s a tendency to think of AI as a replacement for traditional software value. In reality, it’s more of an accelerant. AI is transforming how work gets done inside software. It can automate scheduling, follow up with leads, generate invoices, and even assist in closing sales. But all of those workflows ultimately lead to a single outcome: a transaction. And transactions require infrastructure.

As AI increases the speed and volume of business activity, the importance of seamlessly handling payments, payouts, and financial operations only grows. You don’t just need to enable transactions. You need to manage them intelligently, reconcile them in real time, and provide visibility into what’s happening across the business.

In that sense, AI drives the workflow, but financial technology completes it. We go deeper on this in how AI is transforming embedded payments.

What does the modern multi-product SaaS platform look like?

What’s emerging is a new standard for vertical software companies. The most resilient platforms are no longer built around a single product or revenue stream. They combine multiple layers of value:

Table showing the three layers of a modern vertical SaaS platform: a core system of record that manages the business, embedded financial capabilities for payment acceptance, accounts payable, and payment operations, and AI-driven features that automate workflows.

This combination creates a powerful dynamic. AI increases efficiency and drives more activity within the platform. Financial infrastructure monetizes that activity. And the core software anchors everything in a single, cohesive experience. The result is a more diversified business model, stronger customer alignment, and a much more defensible position in the market.

Why is payment infrastructure the unlock?

Despite the clear benefits, building financial technology in-house is not trivial. It requires navigating regulatory requirements, managing risk, supporting multiple payment methods, and building the operational backbone to handle it all. That’s where infrastructure providers have become critical to the ecosystem.

Companies like Payabli are designed to abstract away that complexity. By offering capabilities like Pay In, Pay Out, and Pay Ops in a unified platform, they allow software companies to embed financial functionality without having to become full-fledged payments companies themselves.

This isn’t just about faster time to market, though that matters. It’s about enabling software companies to deliver a seamless, end-to-end experience for their customers, from the moment work is created to the moment money moves and is reconciled. And the opportunity sits squarely with this layer: Bain estimates revenue for software platforms and the infrastructure powering embedded finance has roughly doubled, from about $22 billion in 2021 toward $51 billion.

What does it mean to become an economic platform?

The broader shift happening right now is not just technological, it’s structural. Vertical SaaS companies are evolving from software vendors into economic platforms. They’re not just enabling workflows; they’re participating directly in the financial lifecycle of their customers’ businesses. That shift fundamentally changes how value is created and captured.

In a world where AI continues to compress the advantage of pure software features, the companies that win will be the ones that go deeper, those that own not just the workflow, but the outcomes tied to it.

AI will reshape software in profound ways. It will make products smarter, faster, and more capable than ever before. But it won’t change the fundamental reality of how businesses operate. Companies still need to get paid. They still need to move money. They still need clarity and control over their financial operations. The opportunity, and increasingly the requirement, is to bring all of that into a single, cohesive platform.

Because in the next era of software, it won’t be enough to simply power the workflow. You have to power the business behind it.

How does Payabli complete the stack?

Payabli provides that layer for vertical software companies. A single API unifies payment acceptance, accounts payable, and payment operations, so a platform can embed and monetize payments without the cost or complexity of becoming a full payments company. Platforms that have made the move see it in their numbers, from Builder Prime’s 1,000% increase in payment volume to Sunbound moving payor adoption from 50% to 90% in under a month. 

If embedded finance is the layer you’re ready to own, book a demo to see what it looks like for your vertical.

And stay tuned for my next article in the series: why the cost-reduction story is only half of it, and how AI is becoming one of the most powerful revenue levers a platform can pull.

Embedded Payables for SaaS Platforms: A Guide

embedded payables

Key takeaways

  • Embedded payables let vertical SaaS platforms run automated vendor payouts inside their product, turning every outbound payment into a revenue stream for the platform and a faster, fully branded payout for the software customer.
  • B2B ACH (electronic bank-to-bank payments) volume grew nearly 10% in 2025, with close to 8.1 billion B2B payments as businesses continue moving away from paper checks. That volume is the wave that embedded payables ride.
  • A single API that covers payment acceptance, accounts payable, and payment operations keeps margin, data, and reconciliation under one roof, so adding accounts payable later does not mean onboarding a second vendor or rebuilding your reporting layer.
  • Owning the outbound side gives the platform a complete view of money flowing through the software customer’s business — in and out — in one place.

Embedded payables let vertical SaaS platforms earn on the money their software customers send out, not just the money they collect. Vendor and subcontractor payouts still run through bank portals, AP tools, and paper checks that the platform never sees. This guide covers how the model works, what platforms earn on each rail, and what to evaluate in a partner.

What are embedded payables for a SaaS platform?

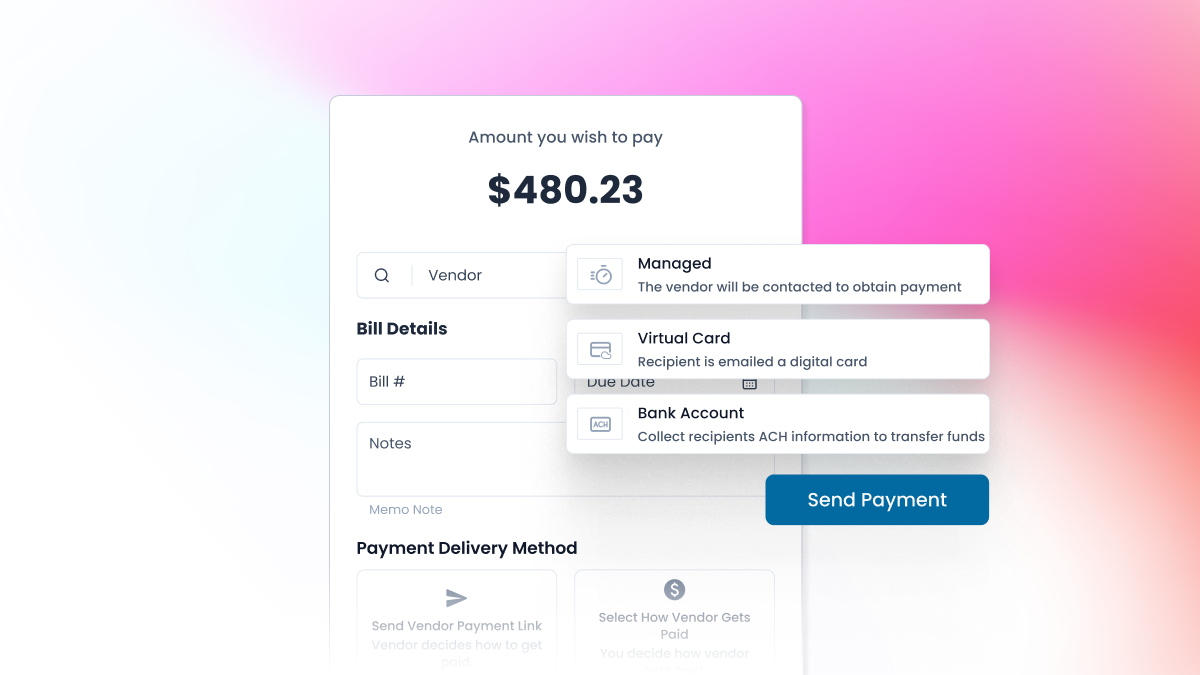
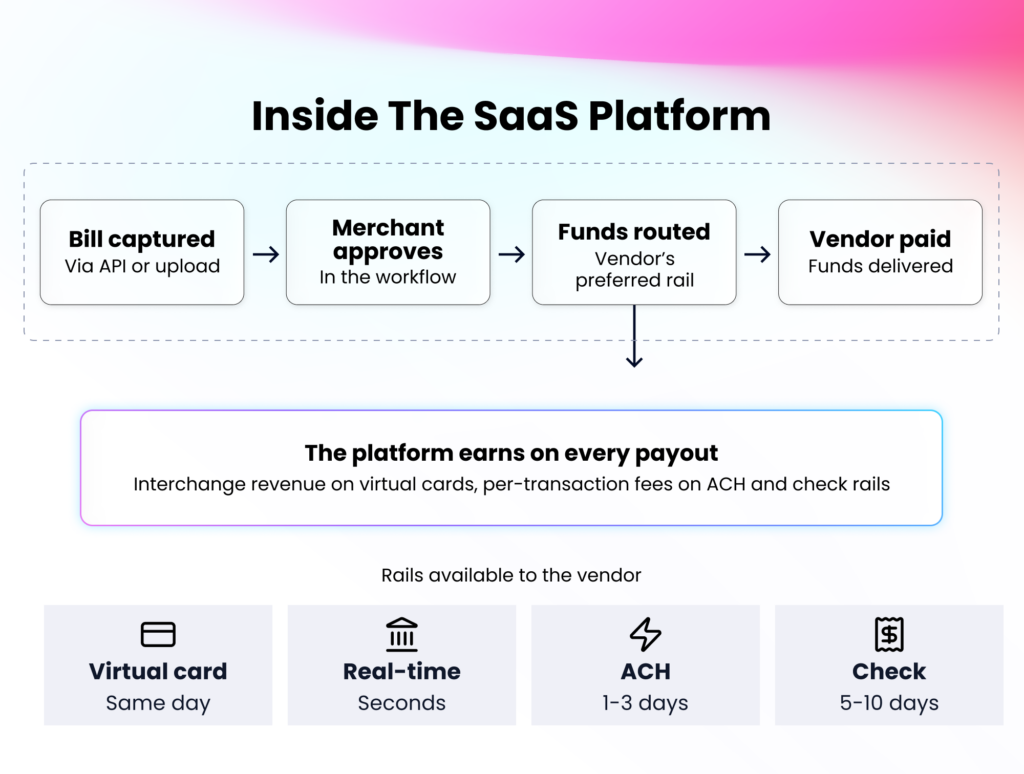
Embedded payables are vendor disbursements that run inside your SaaS product instead of outside it. The software customer approves a bill, the system pays the vendor through the rail the vendor prefers, and the platform earns on the transaction. The per-transaction margin, the vendor data, and the workflow all stay with the platform instead of routing to a third-party tool.

This is the half of embedded B2B payments that most vertical SaaS platforms have not yet captured. Acceptance (Pay In) was the obvious first move because software customers were already collecting money. Payouts are where the software customer’s weekly workflow actually lives, which is exactly why owning them changes the platform’s relationship with its customer.

Where embedded payables show up in a vertical SaaS workflow

The pattern is the same across need-to-pay verticals, just with different vendors at the end of the line. A property management platform pays HOA service vendors and association contractors. A construction platform pays subcontractors and material suppliers on weekly draw schedules. A utility billing or field service platform pays the technicians and crews completing the work order. In every case, the payout sits one click away from the workflow the software customer is already using, and the mechanics behind that one click are what turn it into platform revenue.

How do automated vendor payouts work for SaaS?

A bill enters the system, the software customer approves it, the payment routes through the vendor’s preferred method, and the data posts back to your platform with full remittance details. One API handles the money movement, webhooks fire at each status change, and the activity flows into the same reporting as your acceptance side.

Embedded payables flow for SaaS platforms: bill, approval, vendor payout across virtual card, ACH, real-time, and check rails, with platform revenue on every transaction.

How does money move from your platform to a vendor or subcontractor?

Funds debited from the software customer’s bank account move through whichever rail the vendor accepts (virtual card, ACH, check, RTP, and wire transfers), and settle to the vendor through the partner’s custodial account. ACH (Automated Clearing House) is the bank-to-bank network most vendor payments still ride on. The software customer sees the same status the platform sees, in near real time, without leaving your product.

What payment methods can vendors actually receive?

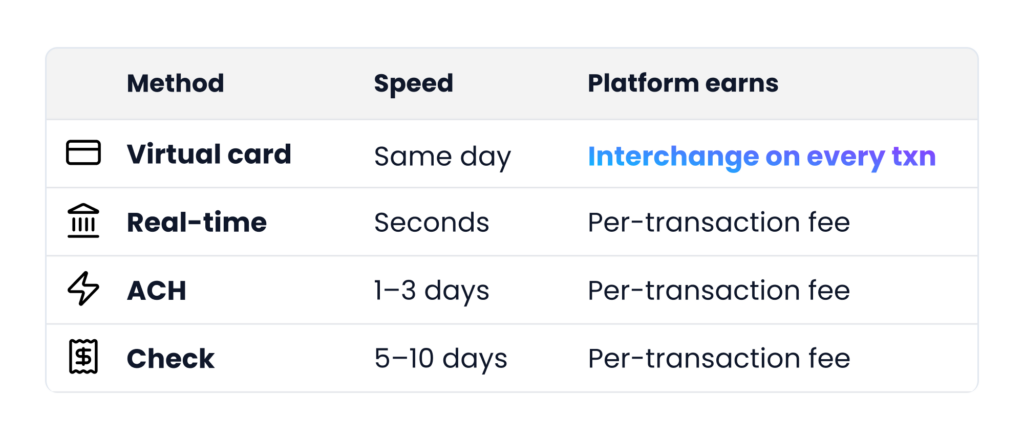
Vendors can be paid through five rails, each with a different speed and platform revenue:

endor payout rails
Alt text: Table comparing vendor payout rails for SaaS platforms across speed and platform revenue: paper check, ACH, virtual card, and real-time payments.

The shift toward digital rails is well underway. According to Nacha, B2B check usage fell from 81% in 2004 to 26% in 2024.

Virtual cards are digital card numbers issued for a single payment or vendor, and every transaction earns the platform interchange, a small percentage of the payment amount. For recurring vendors, Ghost Cards extend that earning model across the full year.

Who handles vendor enrollment and onboarding?

The embedded payments infrastructure partner runs vendor enablement through the product. Onboarding new payees is a configured workflow inside your software, not a manual process for your software customers or a support ticket for your team. Software customers focus on approving payments, not chasing banking details.

For situations where self-service makes more sense, Vendor Payment Links remove the enrollment step entirely. Your software customers send a secure link, the vendor enters their payment details, and funds are disbursed automatically. Collection and disbursement happen in one flow, with no portal to maintain and no enrollment to chase.

What are the benefits of embedded payables for SaaS platforms?

Four benefits drive the case for embedded payables: outbound revenue, stronger software customer retention, transaction data the platform owns, and a vendor experience under your brand.

1. Direct revenue on outbound volume

Every vendor payment earns the platform something. Virtual cards return interchange. ACH, checks, and instant payments return per-transaction fees. For most B2B software customers, outbound volume rivals inbound, which doubles the addressable revenue per customer.

2. Higher net revenue retention (NRR)

Approving bills, managing vendors, and reconciling payments are weekly tasks. When they run inside the software, the platform stops being a tool and becomes a workflow, which is what protects NRR.

3. Transaction data the platform owns

Every payout records which vendor was paid, when, on what terms, and through which rail. That dataset is what unlocks future products like cash flow forecasting, vendor scoring, and working capital.

4. A branded vendor touchpoint

Vendors get paid through the rail they prefer and see the platform’s brand on the remittance. The software customer looks more professional to their own vendors, and the platform’s brand reaches beyond its direct customer base.

What should you look for in an embedded payables solution?

The right embedded payables partner protects your margin, your brand, and your software customer relationship. Three questions cut to whether one fits.

Does it handle vendor enrollment without adding work to your team?

A strong partner runs vendor enablement inside the product, so onboarding new payees is a configured workflow rather than a manual lift for your software customers or a ticket queue for your support team. Enrollment is also where virtual card adoption is won or lost, because every vendor who never gets enrolled is a vendor who keeps getting paid by check, which is the lowest-margin rail on the stack.

Does it support the rails your vendors actually want?

Virtual cards earn the most, but vendors will still ask for ACH and checks. A solution that supports all three lets your platform earn across the full rail mix instead of forcing every vendor onto one method. Real-time payments and wire transfers are the next rail to evaluate, because instant settlement is becoming table stakes in verticals like construction and field service, and the platforms that support it earn on a transaction tier their competitors cannot match.

Does it cover payment acceptance and accounts payable on one stack?

If acceptance is already live, the accounts payable layer should plug into the same API, the same reporting, and the same reconciliation. Splitting them across two vendors fragments software customer pricing, doubles the engineering surface your team has to maintain, and leaves no single partner accountable when margin or reconciliation issues come up. The unified stack is also what makes future products like cash flow forecasting and working capital monetization possible, because both sides of the software customer’s money flow are sitting in one dataset under your control.

How to add embedded payables to your SaaS platform

The integration choice shapes how fast you ship and how much engineering you spend doing it. The right path depends on engineering bandwidth, brand control needs, and how fast you want to start earning on outbound volume.

What integration options can you choose from?

Embedded payables ship through multiple integration paths, ranging from fully custom API builds to prebuilt, ready-to-launch options. Each varies in time to launch, level of UX control, and the engineering investment required. Your provider can walk you through the options that fit your team’s capacity and timeline.

Sunbound launched embedded payments with a single developer and one project manager in under two months and now processes over $1 billion in annual payment volume. For a deeper look at how to sequence the integration, see embedded payments best practices.

How do you pick the right path?

The answer is to pick the path that gets you to live software customers fastest, then upgrade later. Revenue on outbound volume only starts compounding once real payments are flowing, and waiting for a more complex build means months of forgone interchange. Most platforms that start lean ship significantly faster than the ones that try to build everything upfront.

What does your team focus on during rollout?

The provider handles compliance, sponsor banking, and risk monitoring. Your team focuses on the product decisions: who can approve payments, how funds are sourced, what the vendor experience should look like, and how reporting surfaces inside your existing dashboards. Most rollouts run on a weekly cadence with the partner during the build phase, then taper to monthly check-ins once the integration is live and software customers are flowing through.

How Payabli turns vendor payouts into a revenue stream for SaaS

Payabli offers payment infrastructure and monetization for vertical SaaS platforms. Our Pay In / Pay Out / Pay Ops framework unifies payment acceptance, accounts payable, and payment operations under a single API, so platforms capture both sides of their software customers’ money flow without managing multiple vendors or rebuilding their reporting layer.

Virtual cards, ACH, checks, real-time payments, and wire transfers are embedded alongside acceptance flows on the same integration. Vendor enablement, invoice intake, and configurable approval workflows are built in, so software customers see a polished, fully branded product from day one.

Vertical SaaS platforms in property management, construction, utilities, education, and government use Payabli to turn vendor payouts into platform revenue.

If you are mapping where embedded payables fit on your roadmap, book a demo to see what your platform’s payout volume could earn.

Why Implementation Is the Product: The Operational Foundation of Scaling Embedded Payments

By Clayton Smith | Head of Operations at Payabli

I’ll be upfront. I didn’t come up through the payments industry. My background is operations and strategic leadership – the discipline of taking something that works inconsistently and making it work every time, at scale. 

When I joined Payabli nearly four years ago, the company was a small group of scrappy entrepreneurs and a few early adopter partners that believed in the future of embedded payments. Today we’re moving hundreds of billions of dollars across over 100 vertical software platforms serving industries from property management to field services to legal.

I’ve had a front-row seat to what separates embedded payments programs that scale from ones that stall. It almost always comes down to four things:

  • How you implement
  • How you onboard
  • How you scale
  • What you do after go-live

Here’s what I’ve learned about each.

Integration: Implementing for the Long Haul

The first place a payments partnership is won or lost isn’t at the signing table. It’s in the integration.

Every week a partner spends in an integration cycle is a week their merchants are still on a legacy processor, not processing on your platform, and not generating revenue for anyone. Delayed launches don’t just push timelines. They erode confidence. Merchants who expected to go live in October and are still waiting in December start questioning whether they made the right call. Some of them churn before they ever process a single transaction.

The root cause is almost never a bad API. It’s an incomplete product:

  • Documentation that doesn’t match live behavior
  • Sandbox environments that don’t reflect production edge cases
  • A support model that treats integration questions like tickets in a queue instead of blockers with real business impact

At Payabli, our solutions engineering function exists to close that gap before it opens. We scope integrations before a line of code is written, and we ask harder questions upfront:

  • What does your merchant population look like at scale?
  • What billing models do you need to support?
  • What does your support team need to handle merchant issues without escalating to us?

Those answers define the integration. Skip them, and you ship something that works in a sandbox and breaks in production. Speed without completeness isn’t a win – it’s a delayed problem. At Payabli, we don’t trade one for the other.

Merchant Onboarding: From Application to Activation

Once the integration is live, the clock starts again – this time on every merchant waiting to go live.

Merchant onboarding is not just a compliance function. It’s a revenue acceleration function. Every merchant sitting in a pending queue is lost volume. Every onboarding flow that requires manual and time-consuming steps to complete is a merchant who might not finish. Configuration matters here just as much as speed: the right MCC codes, the right processing limits, the right fee structure tied to the partner’s program – these aren’t back-office details, they’re the foundation of a strong merchant relationship.

Underwriting plays a central role that often gets undersold. The goal isn’t just to approve merchants – it’s to approve the right merchants quickly and catch the wrong ones cleanly. A well-structured underwriting policy can clear the majority of merchants automatically, based on defined risk thresholds and data signals, without human intervention. That’s not cutting corners. That’s building a system that scales without adding headcount every time a partner adds merchants.

The outcome of a well-run onboarding process is a merchant who is approved, configured, and activated – processing their first transaction within days of applying, not weeks. Activation rate is the metric we obsess over because it’s often the first signal of whether a payments program is actually working.

Scaling Merchant Migrations: The Bulk Boarding Advantage

Bulk boarding is what happens when a platform has a mature merchant base and needs to move fast. It’s not a variation of standard onboarding – it’s a different operational model entirely, and one of the most powerful capabilities in embedded payments when it runs right.

It’s built for platforms migrating off legacy processors, launching payments to an existing customer base, or absorbing merchants from an acquisition. The merchant list already exists. The business relationship is established. What’s needed is a fast, clean path from data submission to live processing – at volume.

The difference between bulk boarding done well and done poorly is almost entirely operational.

Done poorly: a partner submits a merchant file, gets a spreadsheet back days later with 40% flagged for manual review and no explanation, and starts fielding support calls they can’t answer.

Done well: a clean intake template, automated validation, an intelligent underwriting layer that approves the majority instantly, and real-time visibility into every merchant’s status. 

For Payabli, bulk boarding is a genuine competitive differentiator. It’s what lets a partner with 2,000 merchants convert their entire base in weeks instead of quarters. Whether it’s 30 new customers or 30,000+ migrating at once – I’ve seen it, and we’ve executed.

Post-Live Enablement: The Metrics That Matter

Most implementation conversations end at go-live. Ours don’t.

Getting merchants live is the prerequisite. The actual value of an embedded payments program is built in the months after launch – and it’s measurable:

  • Activation rate tells you if merchants are crossing the threshold from approved to processing.
  • Ninety-day volume tells you if they’re ramping or stalling.
  • Feature adoption – ACH, recurring billing, payouts – tells you how deeply payments are embedded in the merchant’s workflow.

Merchants who use two or more payment rails have materially higher retention than those who only accept card. That’s not an accident – it’s a function of how integrated payments become in their day-to-day operations. Chargeback rate and dispute patterns are merchant experience signals, not just risk metrics. When dispute rates spike for a cohort, there’s usually friction in the payment flow that nobody’s reported yet. Finding that early keeps merchants on the platform – and keeps partners from getting uncomfortable calls.

At Payabli, we help our partners track all of this – not as a reporting exercise, but because these metrics are the early warning system for churn and the playbook for growth. Vertical SaaS platforms who know their activation rate, 90-day volume, and product adoption curve can have confident conversations with their own leadership. Platforms who don’t are flying blind.

The Takeaway 

Implementation is the moment of truth in any payments partnership. The platforms that win in embedded payments are the ones that treat implementation as a competitive advantage, not a line item.

If you’re reading this and thinking “I wish our current payments provider talked like this” – let’s have a conversation. That’s exactly where we should start.