Category: Industry Insights

Choosing the Right Financial Infrastructure Partner To Grow SaaS Revenue

Key takeaways

  • Financial infrastructure is how vertical SaaS platforms monetize the transaction volume already flowing through their product by owning payment acceptance, accounts payable, and the operations that connect them. 
  • Most SaaS platforms only earn from the money their merchants collect. Financial infrastructure opens a second revenue channel for the money merchants send, through the same integration. 
  • Fintech-led vertical SaaS companies hold the strongest retention profile of any category, with 96% gross retention versus roughly 90% for other product types.
  • The right financial infrastructure strategy starts with auditing, where money already moves through your product, not with picking a vendor.

Subscription revenue only grows when you add new customers. Financial infrastructure revenue grows every time your existing merchants process a transaction. Median SaaS growth rates have settled at 26%, down from 30% two years ago, and net revenue retention across the industry has compressed to 101%. The SaaS platforms pulling ahead are not adding features. They are building a financial layer that earns on every transaction their merchants process.

This blog covers what financial infrastructure means for a SaaS platform, how it generates revenue, and how to build a strategy around it.

What is financial infrastructure for a SaaS platform?

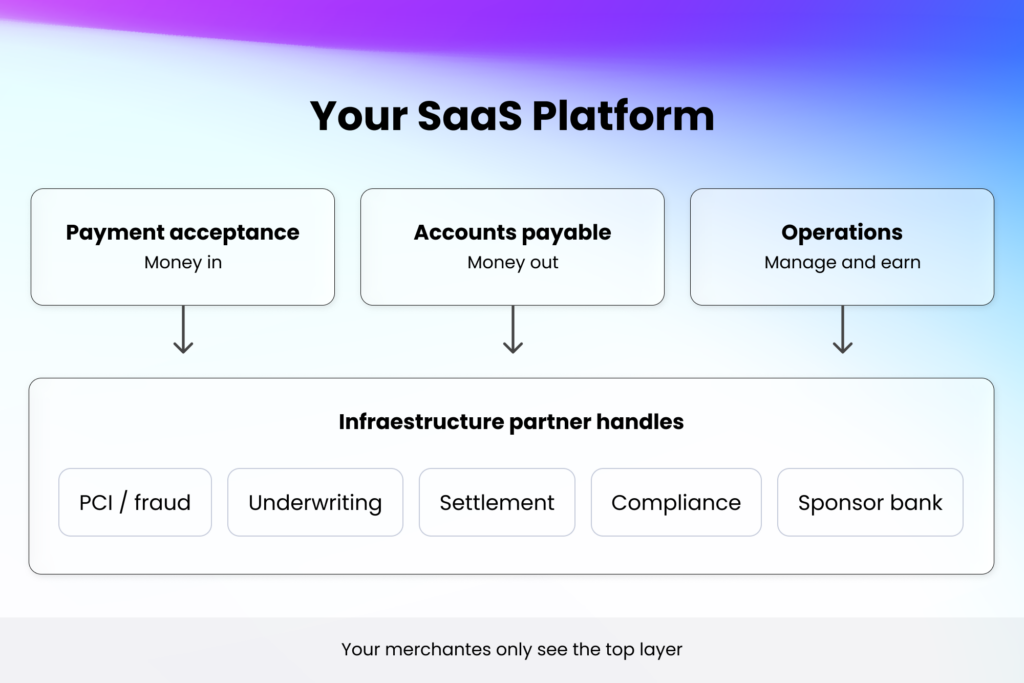
Financial infrastructure is what lets your SaaS platform accept, send, and earn from your merchants’ money. It covers three functions: payment acceptance (Pay In) from your merchants’ customers, accounts payable (Pay Out) to their vendors and partners, and the operational layer (Pay Ops) connecting both, including onboarding, underwriting, risk, billing, and reconciliation. 
Financial infrastructure vs. payment processors

A payment processor handles one job: moving money from point A to point B. Your SaaS platform sends a transaction, the processor routes it, and a third party collects the margin.

With financial infrastructure, the economics start to shift. Your platform sets merchant pricing, the infrastructure partner processes through a unified API, and you keep the spread between the two. You also own the transaction data, which means you can optimize pricing by segment and track adoption across your merchant base.

What makes financial infrastructure a revenue layer for SaaS?

Subscription revenue grows when you add customers, while payment revenue through financial infrastructure grows when your existing customers grow, with no upsell and no new contract.

That compounding dynamic is why fintech-led vertical SaaS companies hold the strongest retention profile of any category, with 96% gross retention versus roughly 90% for other product types, according to the benchmark report by Tidemark. The more financial workflows a merchant runs through your SaaS platform, the better their experience, the more revenue you earn, and the harder your product is to replace.

How does financial infrastructure actually generate revenue?

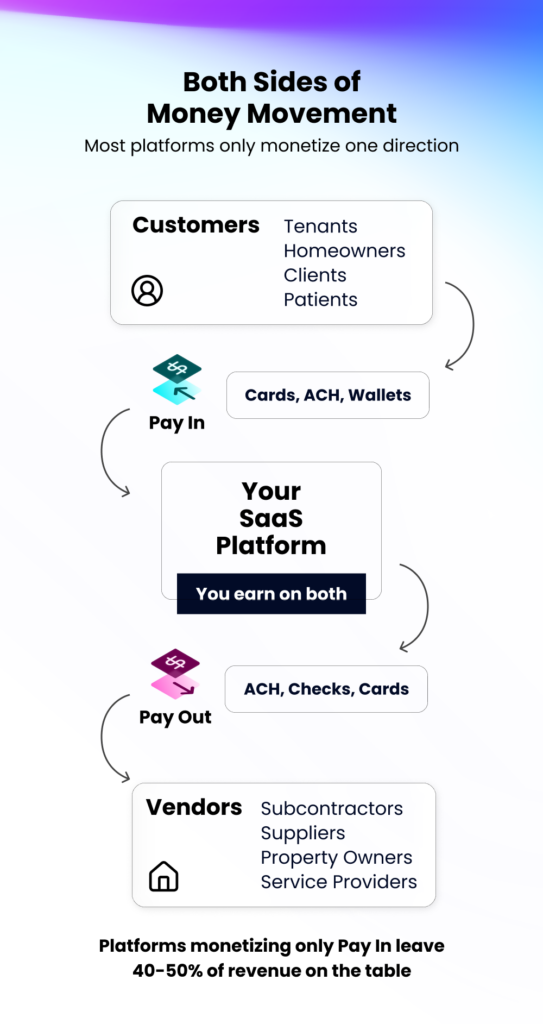
SaaS platforms generate revenue from financial infrastructure on two sides: the money their merchants collect and the money their merchants send. Most platforms only monetize the first.

Transaction spread explained: where SaaS payment margin comes from

Every payment your merchants process through your SaaS platform has an underlying cost. Your platform charges your merchants a rate above that cost. The difference is your margin.

That margin exists on both sides. On the Pay In side, you collect margin on every transaction your merchants collect. On the Pay Out side, when merchants pay vendors through your platform, you earn on each outbound payment too.

In practice, the key variable in SaaS payment margin is not the rate. It is volume. A SaaS platform with 200 merchants processing $300,000 each annually sits on $60 million in volume. That is revenue your subscription model cannot produce without adding new customers.

Which vertical SaaS industries earn the most from embedded payments?

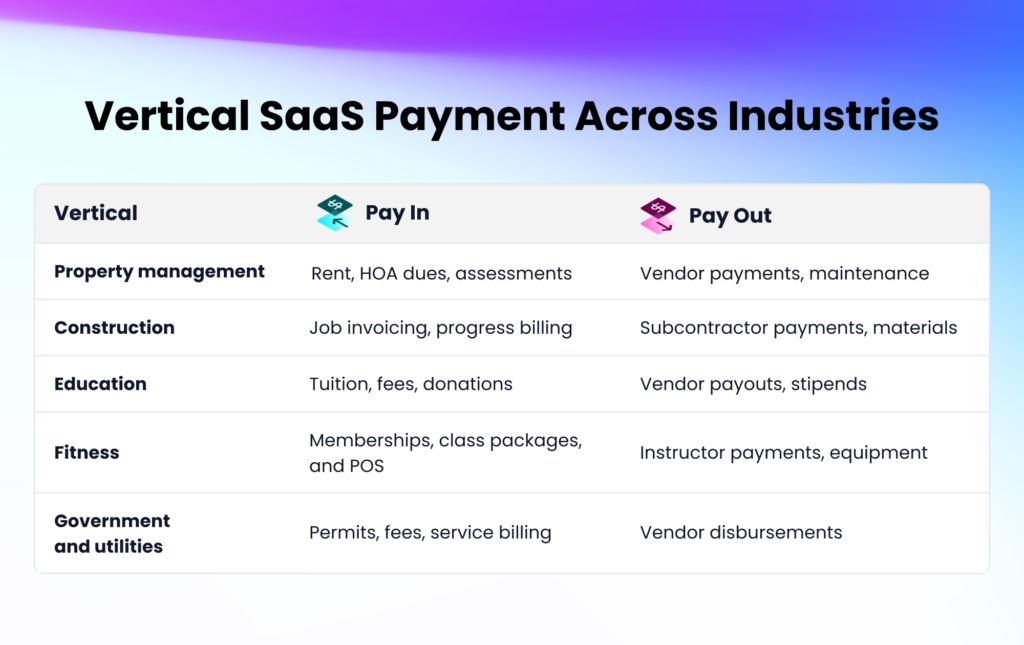
In vertical SaaS, the highest-value financial infrastructure opportunities sit in industries where merchants cannot operate without processing payments through the platform. Here are some of the verticals where SaaS platforms generate revenue on both sides:
How do you build a financial infrastructure strategy for SaaS?

Most SaaS platforms pick a vendor before they know what they are monetizing. The sequence below starts with scope, not technology.

Step 1: Audit where money already moves through your product

Before evaluating vendors, define the scope of your financial infrastructure. Map where merchants collect money, where they send it, and where they leave your product to do either. That map determines whether you start with acceptance only or launch with acceptance and accounts payable together.

Step 2: Choose your integration model

There are three primary paths. A hosted solution gets you live in one to two weeks with minimal engineering lift — Payabli manages underwriting, risk, and support while you start generating revenue immediately. Embedded components go deeper, embedding payments natively into your platform in four to six weeks, with the flexibility to take on more operational ownership at your own pace. An API build gives you full control over every touchpoint — custom underwriting, risk, pricing, and merchant lifecycle management — for platforms ready to operate like a full-stack payments business.

What makes Payabli different is that you’re not locked into one path. You can start hosted, layer in embedded components, and graduate to API when you’re ready — without ever needing to re-platform.

Step 3: Set pricing and revenue share that scales with your merchants

Your pricing model shapes your margin at every scale. Payabli gives you full visibility into your cost structure so you can build pricing around your vertical, not a generic blended rate, and set different rates for different merchant segments. Whether you’re running flat rate, tiered pricing, or interchange plus, the right infrastructure gives you the pricing tools and cost transparency to make this practical from day one.

Step 4: Make payments the default

None of this matters if your merchants don’t actually activate. Payments should show up where the work happens, inside the invoice, inside the vendor payout, not behind a settings tab. Set enrollment as the default during onboarding and track merchant activation rate from day one. Activation rate is the percentage of your merchants actively processing through your platform. It belongs next to retention and NRR on your dashboard.

How do you evaluate a financial infrastructure partner for SaaS? 

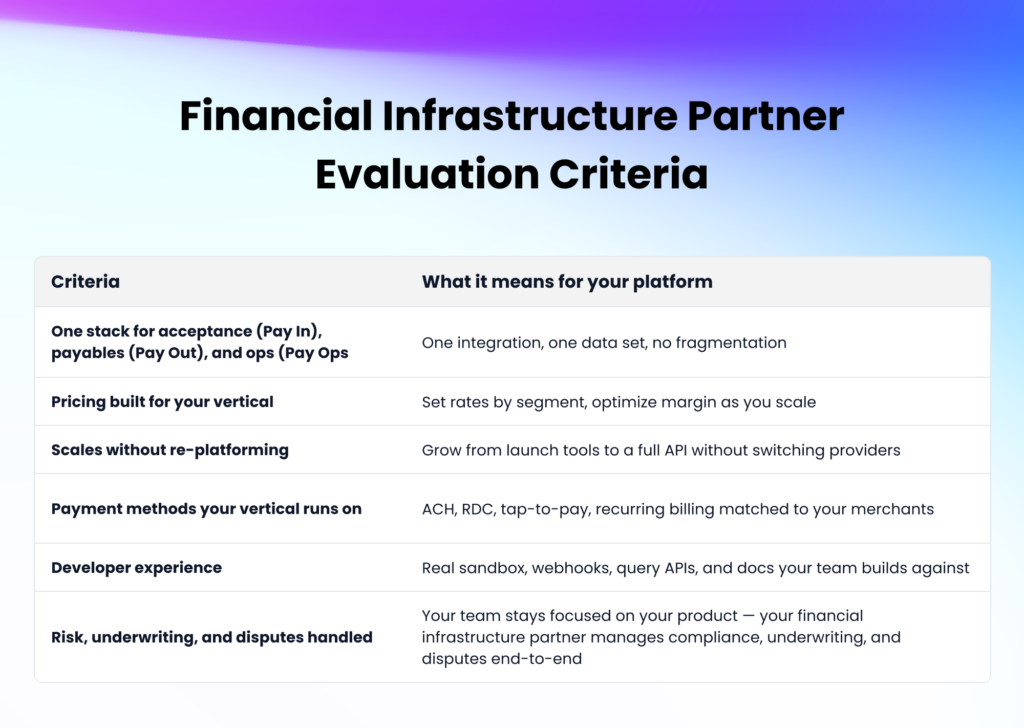
You have the strategy. Now you need a partner who can execute it. Get this wrong, and you rebuild. 
How can Payabli help build your SaaS financial infrastructure?

Payabli was built to help vertical SaaS platforms do exactly what this blog describes. Payment acceptance, accounts payable, and payment operations run through a single API, so you do not stitch together three vendors to cover what should be one infrastructure layer.

Beyond the integration, Payabli gives you full visibility into your cost structure, segment-level pricing controls, and interchange optimization guidance so your platform is built to capture margin from day one. Every partner gets a dedicated payments team that knows their vertical and helps shape a go-to-market strategy around payments — not a generic onboarding checklist. The conversation starts with where you are and where you want to go, not with a product pitch.

Request a demo, and we will map the financial infrastructure opportunity for your platform.
How Embedded Payments Increase Vertical SaaS Valuation

Brad Weekes, Managing Director at Software Equity Group, brings a deeply informed perspective on how fintech is reshaping vertical SaaS business models and valuations.

Drawn to the intersection of technology, strategy, and finance, Brad has tracked the rise of integrated payments for over a decade. He spent his early years analyzing public markets while building a deep, hands-on understanding of software. He helped acquire companies, scale operations, and ultimately navigate the full lifecycle—from growth to acquisition and IPO.

Today at Software Equity Group, Brad advises B2B SaaS and embedded payments companies, typically in the $5M to $50M ARR range, on majority transactions and exit strategy. 

The Shift from SaaS to Embedded Fintech

Back in 2018, Brad recalls working with a higher education software company.  The company’s core offering allowed people to register for classes online.  However, in the registration workflow, when payment was due for the class, the company handed the course registrant off to another provider to accept the payment. It was a classic scenario at the time, and one that sparked a conversation during the valuation process and with buyer conversations about how payments could be embedded in the workflow.  The acquiring company spent a lot of time on payments, far more than there was any revenue to show for it. 

Eight to ten years ago, vertical SaaS companies were starting to think about integrating payments as part of their offering and acquiring companies were intrigued.  Today, payments are no longer optional.  They are a primary driver of value. 

Knowing embedded payments should be core to your product and its future is one thing, but actually executing on an embedded payments strategy (or additional fintech offerings) requires planning and execution.  

From a product perspective, Brad notes it’s never too early to add payments.  In fact, if you start too late, you won’t have the adoption rates or revenue proof points needed.  

“You need traction—not a story.”

When it comes to customer adoption, that’s where timing really matters.  Brad stresses that traction matters more than vision.  He warns that buyers will discount “story-only” opportunities.

Beyond payments, fintech offerings like lending (marketplace-driven) and insurance (growing quickly) are emerging as additional value drivers.  But, payments still remain the most proven and scalable entry point.

If you’re a vertical SaaS founder starting or evolving your payments and embedded fintech offerings, Brad suggests you keep a few payment-specific KPIs in mind. 

Payments-Specific Metrics:

  • Payment penetration (critical)
  • Total payment volume (TPV)
  • Net take rate trends
  • Cohort adoption over time

Common Mistakes Founders Make 

When embedding payments into your product to boost valuation and increase exit opportunities, there are a few simple mistakes you can easily avoid.  

Brad has seen founders say, ‘‘we’ll just plug in payments here,” but he cautions it’s not that easy. There’s a lot underneath the hood. Here’s Brad’s quick guide to common payments mistakes and how to avoid them.

Underestimating Complexity

Risk: Payments ≠ simple plug-in

Opportunity: Think through operational, compliance, and go-to-market challenges

Low Penetration Across Customer Base

Risk: Starting too late to gain traction and build strong adoption rates.  Reduces credibility. Opportunity: Embed payments early. Draft and execute an adoption playbook.

Treating Payments as a Bolt-On

Risk: Lack of deep workflow integration

Opportunity: Make payments a critical part of the workflow. The stickier payments are, the harder they are to rip and replace. 

Why Embedded Payments Increase Company Value

Seeing how embedded payments drive immediate revenue, increase retention, and expand gross profit, it’s no surprise they are a primary driver of value.  As Brad notes, embedding payments is effectively “found money” from your existing customer base. 


“These SaaS companies find a new revenue stream with payments—often overnight. If they have an existing install base, they flip the switch on payments and NRR goes through the roof, and their gross profit grows dramatically.”

Embedded payments also help deepen product integration and customer retention.  Your solution shifts from being a tool to a mission critical system thanks to tightly integrated workflows.  

You also unlock new ways to monetize customer activity.  The typical SaaS model is usage-based – depending on growth of seats.  With embedded payments, you’re opening up possibilities of usage-based and outcome-based pricing.  

“Now you have not only the software platform, but payments—which is a critical part of the workflow. Ripping that out becomes much more difficult.”

To ensure you maximize your valuation, Brad suggests you keep a few of these key metrics strategic buyers will scrutinize in mind.  

Financial Metrics 

  • Gross revenue vs. net revenue
  • Gross margin of payments stream
  • Cost structure (processing, interchange, etc.)

SaaS + Payments Combined Metrics

  • Net Revenue Retention (NRR)
  • Gross Revenue Retention (GRR)
  • Rule of 40
  • Gross margin profile

As you build out your embedded payments offering and your overarching pricing models, Brad does caution not to get too creative.  He’s seen a few founders over-optimize pricing models (i.e. “free SaaS, monetize only payments’) to the point that it creates a lack of revenue stability and buyer skepticism. 

“When you get too creative, you add noise. Buyers start asking, ‘why are you doing this?’ It just creates more questions than value.”

SaaS companies are facing a lot of pressure today as AI takes over that pricing models should be more outcome-based. There’s two sides to that coin because while buyers and investors might find the increased gross profit margin attractive, it’s likely that if you view that revenue stream like an annuity it’s not considered as valuable as contracted SaaS. 

When we get a payments company with transaction or usage based activity, we try as much as we can to make it look like contracted recurring revenue. We want this payments revenue stream to look exactly like this recurring SaaS stream. Brad often argues embedded payments revenue is better because the NRR goes through the roof compared to contracted SaaS, which is limited by price increases that are CPI basis.

Tracking these metrics isn’t just good hygiene — it’s how you build a credible exit narrative. To make it easier, we put together a Payments Cohort Analysis Template you can use to track payment penetration rates, TPV trends, net take rate, and cohort adoption over time. It’s built around the exact data points acquirers will ask for.

Download the Payments Cohort Analysis Template →

Key Takeaways for Vertical SaaS Founders

  • Payments can materially increase enterprise value
  • Traction > vision when it comes to valuation
  • Multiples can vary dramatically — working with an investment banker who understands embedded payments and can shape the narrative around your payments business may significantly improve your outcome

The best model combines:

  • SaaS stability
  • Payments upside
  • Deep integration beats surface-level add-ons
  • Start early — but execute thoughtfully

Ready to Build Payments Into Your Platform?

Brad’s advice is clear: the window to get ahead of this is now. Payments aren’t a feature you add when you’re ready to sell — they’re the infrastructure that makes your platform worth buying.

If you’re a vertical SaaS company looking to embed payments the right way — with the workflow integration, compliance backbone, and financial infrastructure that actually moves the needle on valuation — that’s exactly what Payabli is built for.

Book a demo with the Payabli team →

Meet Your New Fractional Head of Payments: Payabli’s Partner Development Team 

By Emi Keshler | Director of Partner Development at Payabli 

I spent the better part of a decade in vertical software startups. Small teams, scrappy budgets, and a payments operation that was usually one person’s problem – mine.

I’ve been the one fielding 2am “fire alarm” calls. I’ve negotiated seven-figure payments contracts. I’ve handled activation rates, merchant onboarding, KYC escalations, chargeback disputes, and compliance audits – often as the only person in the entire company who understood why any of it mattered. I’ve supported, organized, scaled, innovated, optimized, strategized, documented, and implemented. And I did most of it while flying blind.

I am, without question, a payments industry lifer.

But here’s what I’ve learned from all of it: you don’t have to be.

If you’re ready to unlock the real power of embedded payments in vertical SaaS – and you’ve been looking for someone to hand you a map – allow me the pleasure of introducing Payabli’s Partner Development Program.

Why Partner Development Exists

Here’s a scenario I’ve lived through more times than I can count.

When something breaks in your payments program – activation rates drop, a cohort of merchants stalls in KYC, a competitor is undercutting your pricing – who’s responding? If the honest answer is “whoever has the most bandwidth right now,” you don’t have a payments program – you have a payments feature holding on by a thread.

What you actually need is a Head of Payments (HOP). Whether the title is VP of Payments, GM of Fintech, or Payment Operations Manager – the role is the same. It’s the person who already knows what’s wrong before you call them. Who’s already looked around every corner, built a payments strategy, and is ready to move. Research consistently shows that a dedicated subject matter expert is the strongest predictor of successful payments outcomes.

But what if you don’t have that person in-house (yet?) That’s exactly why Payabli built our Partner Development Program.

What Does Partner Development Do?

Think of us as your embedded strategic payments partner – like a fractional Head of Payments who already knows your business. We put on the “Head of Payments hat” and lock arms with you to build a best-in-class payments program from the ground up. Here’s what that looks like in practice:

We start with an honest assessment of your payments program stands today and set clear goals for where you want it to go. Within 48 hours you’ll receive a full strategy and action plan with projected outcomes in 6, 9, or 12 months.

From there, we work alongside you through every phase:

  1. Evaluation & Goal Setting – understanding your current state and defining what success looks like
  2. Gap Analysis & Strategy – a comprehensive look at where you’re leaving revenue, efficiency, or merchant experience on the table
  3. Weekly & Milestone Check-Ins – ongoing accountability and course correction as you grow
  4. Strategy Execution Tools – hands-on training, custom white-labeled collateral, reporting, business case support, and more
  5. Optional Co-branded Marketing – showcasing your competitive growth to your own customers and prospects

This is not consulting in the traditional sense. There are no billed hours or recommendations without a shared stake. We’re in the weeds with you – reviewing your merchant lifecycle, diagnosing underperformance, and staying accountable to outcomes for months.

Our gap analysis is comprehensively supportive of immediate results, plus long-term scalability. Examples include:

  • Sales: Positioning, talk tracks, incentive structures, negotiation levers, and value-selling training so your team actually knows how to sell payments.
  • Merchant Onboarding: Reducing friction from first touch to activation through KYC/KYB education, completion rate optimization, and follow-up sequencing
  • People & Support: Tier 1 and Tier 2 support protocols, payments training, emergency preparedness, hiring tips, and the tools your team needs to diagnose and resolve issues fast
  • Reporting & Analytics: KPI frameworks, data monitoring, quality control, underperformance diagnostics, and reconciliation to keep your program healthy and accountable
  • Merchant Experience: Competitive analysis, product prioritization, vertical-specific optimization, business case development, and the full Payabli Pay In, Pay Out, and Pay Ops framework
  • Account Management: Retention, renewals, feature adoption, QBRs, and performance monitoring to protect and grow revenue over time
  • Risk & Compliance: PCI best practices, chargeback protocol, Nacha compliance, and merchant offboarding done right

The Partner Development team has spent years solving these problems the hard way – trial, error, and a lot of late nights. We didn’t always have the answers. But we always found them. Now that experience lives in a playbook, and it was made for you.

Come Grow With Us

We are so excited to formally launch our Partner Development Program – and the results from our early partners speak for themselves. They’re growing faster, activating merchants more quickly, and preventing churn before it starts.

If you’re a software operator who has ever stared down a room full of salespeople who didn’t care about payments, scrambled to explain what a good activation rate even looks like, or just wished you had a payments expert in your corner who understands your vertical – that’s exactly who we built this for.

Your payments program deserves more than bandwidth. Let’s give it a strategy.


Emi Keshler is the Director of Partner Development at Payabli. After 7 dog years in the vertical startup world, she joins Payabli to build Partner Development as a dedicated line of business.

PayFac-as-a-Service for Vertical SaaS: a complete guide

Key takeaways

  • PayFac-as-a-Service offers vertical SaaS platforms PayFac-level merchant ownership, pricing control, and white-labeled branding without the 12 to 18-month registration period or full compliance obligation.
  • Payment processing revenue through software vendors in the U.S. has grown at 20% annually, reaching an estimated $16 billion in 2025 (McKinsey).
  • With PayFac-as-a-Service, the platform controls merchant pricing, onboarding, and the merchant relationship while the infrastructure partner manages sponsor bank relationships, regulatory compliance, and underwriting.
  • The right PayFac-as-a-Service models unify payment acceptance (Pay In), accounts payable (Pay Out), and payment operations (Pay Ops) through a single API, giving platforms a complete payments business.

Every vertical SaaS platform eventually reaches a turning point where subscription revenue no longer suffices to fund the next stage of growth, while the payment volume flowing through the platform emerges as a revenue opportunity greater than the software itself. The next move is to become a payment facilitator, the entity that onboards sub-merchants, earns a margin on every transaction, and controls pricing. Full PayFac registration is the more resource-intensive route, requiring significant time, infrastructure, and compliance overhead. PayFac-as-a-Service is a faster path to the same revenue opportunity, without the organizational lift of becoming a registered PayFac.

In this blog, we will walk you through everything you need to know about PayFac-as-a-Service and how vertical SaaS platforms can embed payments, capture transaction revenue, and go live – while preserving the option to graduate to a registered PayFac when the time is right.

How do PayFac-as-a-Service and SaaS platforms work together?

For SaaS platforms, PayFac-as-a-Service is the unlock: embed payments into the product, own the sub-merchant relationship, and earn revenue on every transaction customers process without building the underlying infrastructure. Payment processing revenue through U.S. software vendors is projected to reach $16 billion in 2025, growing at 20% annually (McKinsey). Most of that margin is not going to the platforms generating value.

A Payment Facilitator (PayFac) holds a master merchant account with an acquiring bank, onboarding sub-merchants under it, and earning a margin on every transaction. Full registration delivers that control but takes 12 to 18 months and significant capital to get there.

PayFac-as-a-Service splits the model between two parties. The provider manages the sponsor bank relationship, compliance, regulatory reporting, and processing infrastructure. For a SaaS platform, this means payments live inside the product: the platform configures sub-merchant onboarding, sets pricing, controls the payment experience, and earns on every transaction processed, without building or maintaining the infrastructure behind it.

PayFac-as-a-Service vs. Registered PayFac for SaaS providers

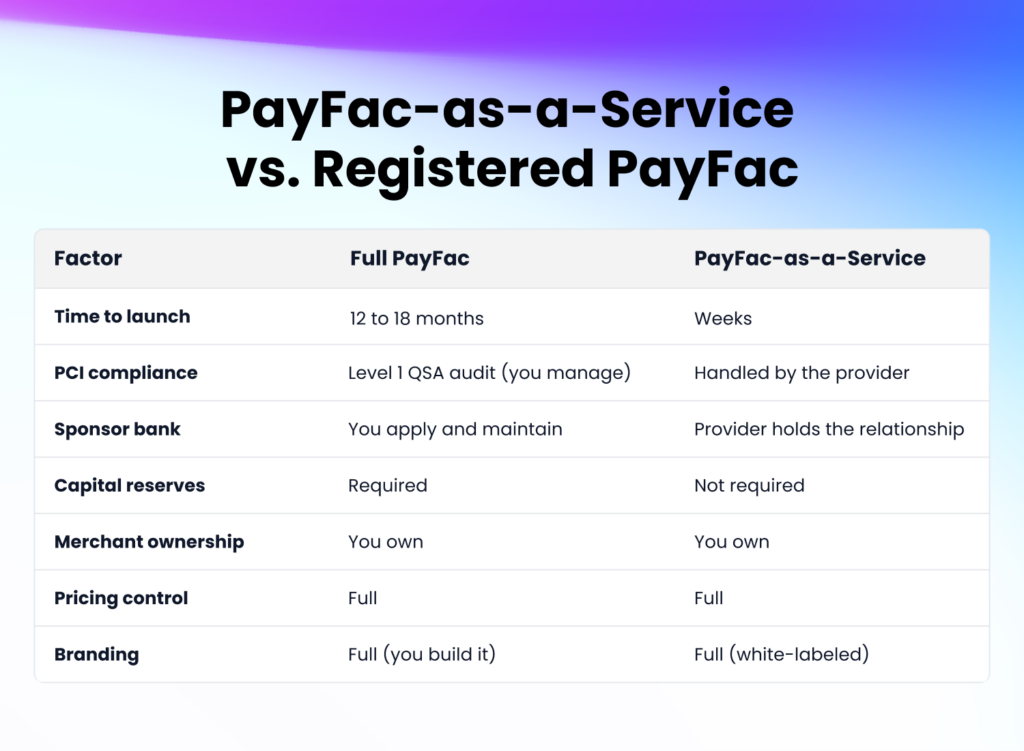
Full registration and PayFac-as-a-Service deliver the same sub-merchant economics. What separates them is time, capital, and compliance overhead.

A comparison table showing seven factors including time to launch, PCI compliance, sponsor bank, capital reserves, merchant ownership, pricing control, and branding, across Full PayFac registration and PayFac-as-a-Service.

PayFac-as-a-Service vs. Full PayFac: Which suits your SaaS platform?

Full registration is typically suited for platform processing at scale, with the internal resources to manage ongoing compliance requirements. For vertical SaaS companies in property management, field services, education, utilities, and government, PayFac-as-a-Service delivers the same economics without pulling engineering resources away from the core product, while preserving the option to graduate to a registered PayFac when the time is right.

Why are SaaS platforms adopting PayFac-as-a-Service?

PayFac-as-a-Service adoption among vertical SaaS platforms has accelerated sharply, fueled by two driving factors: the revenue opportunity is too large to leave on the table, and the sub-merchant experience gap is becoming a retention problem.

Payments revenue without the compliance burden

Over 90% of U.S. sub-merchants now use an ISV solution for payments or business management, per McKinsey’s 2025 ISV maturity analysis. Platforms on a referral model earn a small fee for directing sub-merchants to a third-party processor. Platforms on PayFac-as-a-Service capture the margin between wholesale and sub-merchant rates on every transaction. A platform processing $100 million annually at 100 basis points generates $1 million in transaction revenue without adding a single customer.

The compliance argument is equally clear. Full registration requires a Qualified Security Assessor (QSA) audit for PCI Level 1, NACHA compliance, sponsor bank approval, KYC/KYB on every sub-merchant, and ongoing chargeback management. Platforms that stay on referral models also lose access to Level II and Level III interchange optimization, meaning they pay more per transaction than they need to while earning nothing on the volume. PayFac-as-a-Service removes the compliance burden and unlocks the margin optimization that referral models never could.

A branded sub-merchant experience you control

When a third party handles payments, sub-merchants onboard outside the platform, see a different brand at checkout, and contact a different support team for issues. The platform loses visibility into the payment lifecycle, and there is no way to fix the experience gap that the sub-merchant notices. With PayFac-as-a-Service, payments are white-labeled inside the platform. The experience is smooth, the relationship stays with the platform, and sub-merchants processing payments inside the software are significantly harder to churn. That retention shows up directly in net revenue retention numbers and valuation multiples.

The data cost is just as high. Without embedded payments, reconciliation stays manual, reporting lives outside the platform, and sub-merchants never get the payment visibility they expect from software they rely on daily.

What do I look for in a PayFac platform as a SaaS provider?

Not every PayFac-as-a-Service provider is built for vertical SaaS. Some are horizontal processors that have retrofitted embedded payments as an add-on. Here are the factors that separate a purpose-built infrastructure partner from a generic one:

Pay In, Pay Out, and Pay Ops under one roof

Practically, a complete PayFac-as-a-Service solution covers three areas: payment acceptance (Pay In), accounts payable (Pay Out), and payment operations (Pay Ops). The platform gets revenue from both the inbound and outbound payment flow, while the provider handles onboarding, risk, billing, compliance, underwriting, and reporting behind the scenes.

APIs and no-code options for faster integration

The strongest models offer a full API for maximum control, no-code embedded components for speed, and a white-label portal for platforms that launch with minimal engineering lift. Query APIs for transaction data and webhooks for near-real-time event notifications are baseline requirements for any production-grade integration. The result: faster integration, less engineering overhead, more time building the core product.

Vertical-specific payments customization

Generic payment infrastructure is not built for how vertical SaaS platforms operate. A construction platform handling progress billing has different requirements than a property management platform that collects HOA dues. The ideal provider offers support for compliant surcharge and service fee pricing for regulated industries, bulk sub-merchant onboarding, and Level II and Level III data submission for interchange optimization on B2B card transactions.

How do I make PayFac-as-a-Service work for my SaaS platform?

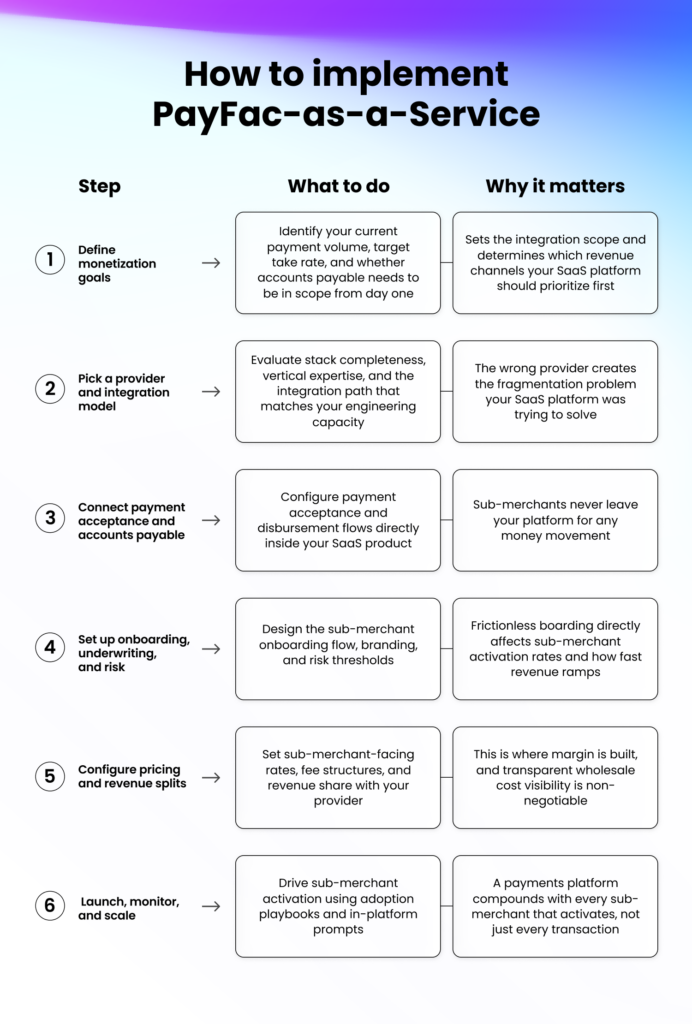
Getting from the decision-making phase to live transactions is straightforward when the sequence is right. Here is how vertical SaaS platforms implement PayFac-as-a-Service:

A six-step implementation table covering what to do and why it matters, from defining monetization goals through launch and scale.

What does PayFac-as-a-Service look like in practice?

The best way to understand what PayFac-as-a-Service delivers for vertical SaaS is to look at platforms that have already made the switch. The results speak for themselves.

How Builder Prime grew payment volume by 1,000%

Builder Prime is a CRM and project management platform built for home improvement contractors. Before Payabli, payments were handled through a third-party processor. Sub-merchants onboarded outside the platform, the experience was disconnected, and Builder Prime had no visibility into payment activity or margin on transactions.

After embedding payment acceptance directly into its platform through Payabli, sub-merchants could accept cards, ACH, and checks inside the product they already used daily. The payment experience was white-labeled, the sub-merchant relationship stayed with Builder Prime, and the platform started earning on every transaction processed. Payment volume grew by 1,000% and embedded payments became a core retention driver, not just a processing utility.

Read the full Builder Prime case study.

How Sunbound scaled with embedded payments

Sunbound is a modern senior living finance platform. Before Payabli, payments ran through Stripe outside the core product, limiting pricing flexibility and leaving margin on every transaction with someone else.

Sunbound integrated with Payabli in under one month with a single developer and one project manager. Payment acceptance, sub-merchant onboarding, and reporting all moved inside the platform. The impact on sub-merchant activation was immediate: before Payabli, around 50% of payors used the payment flow. After embedding payments inside the platform, that number climbed to 90%.

Read the full Sunbound case study.

How Payabli powers PayFac-as-a-Service for SaaS

The right PayFac-as-a-Service partner gives your platform the economics, the sub-merchant experience, and the operational infrastructure to run a payments business without becoming one. Here is how Payabli delivers that for vertical SaaS.

One API for Pay In, Pay Out, and Pay Ops

Most platforms that try to build a payments business end up managing six or more vendor relationships. Payabli replaces that with one. A single unified API covers payment acceptance, accounts payable, and payment operations, so your team integrates once and owns the full payments experience from day one.

Built for vertical SaaS

Payabli powers over 70 vertical SaaS platforms across property management, field services, construction, education, and government. Customers, including Roofr, BuildOps, PayHOA, and Builder Prime, have turned payments into a core revenue stream without building the infrastructure themselves. See how Payabli works for SaaS companies.

Go live fast with hands-on support

Payabli partners have gone live in under a month with one developer and one project manager. A dedicated team is assigned from day one, not a ticketing queue, with support via email, Slack, and phone. Book a demo to see what the economics look like for your platform.
How to Monetize Payments: A Guide for SaaS Platforms

Learn how to monetize payments in your SaaS platform

Key takeaways:

  • SaaS platforms monetize payments by owning the infrastructure that their merchants already use to collect and send money. Every transaction becomes a revenue event instead of a cost.
  • Adding payments to your platform can increase revenue per user by 2 to 5 times without adding a single new customer.
  • The full revenue opportunity sits across three layers: payment acceptance (Pay In), accounts payable disbursements (Pay Out), and pricing tools (Pay Ops).
  • The most common monetization failures: too many vendors splitting your margin, a lack of outbound payment strategy, and infrastructure not built for your specific vertical.

Your platform already has transaction volume running through it. Every invoice your merchants send, every transaction they collect, and every vendor payment they make is value your platform unlocks but does not capture. The margin on those transactions exists whether you capture it or not. Right now, a payment processor is keeping it. 

This guide shows you where that revenue sits, what it takes to own it, and how to implement it without a multi-year engineering project.

What does it mean to monetize payments for a SaaS platform?

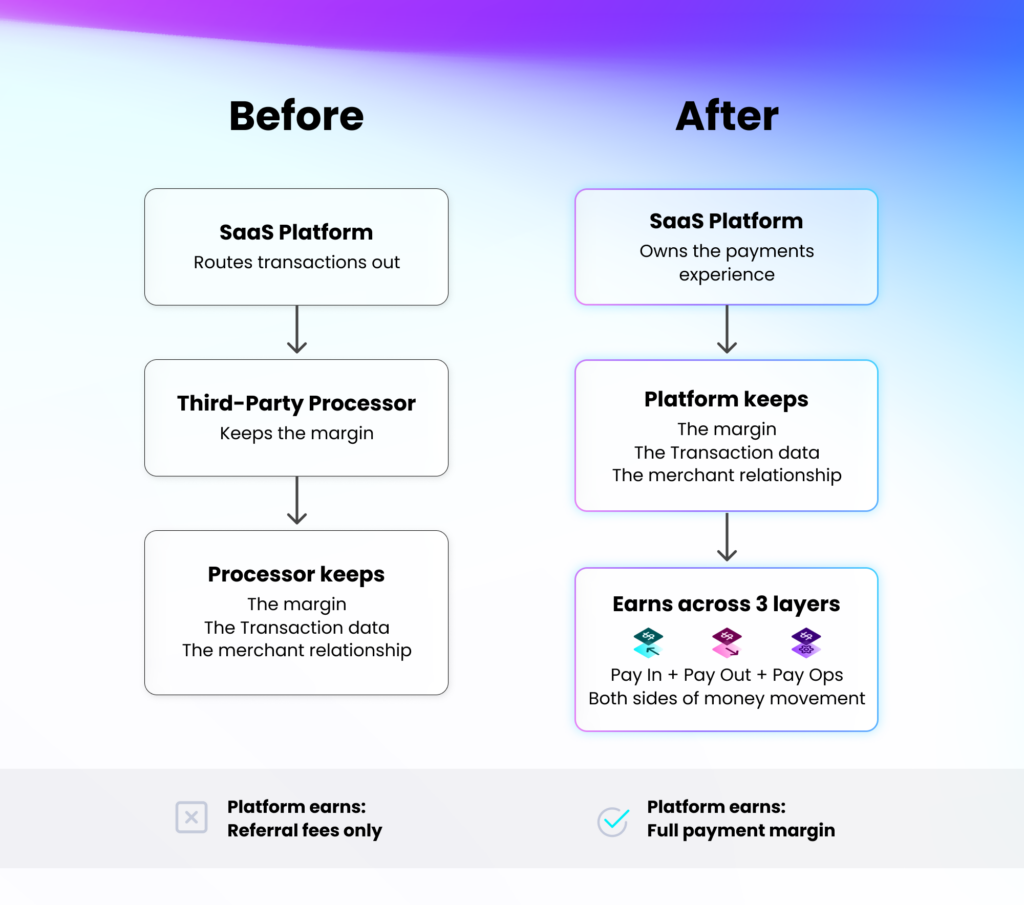
Most SaaS platforms already process payments. Most leave the revenue from them on the table. The difference is not technical, but it is who owns the margin. When a third-party processor handles your transactions, they keep the spread, the data, and the merchant relationship. When you own the infrastructure, you keep all three. The right time to make that shift is before your transaction volume becomes someone else’s moat.

How do payments become a revenue stream?

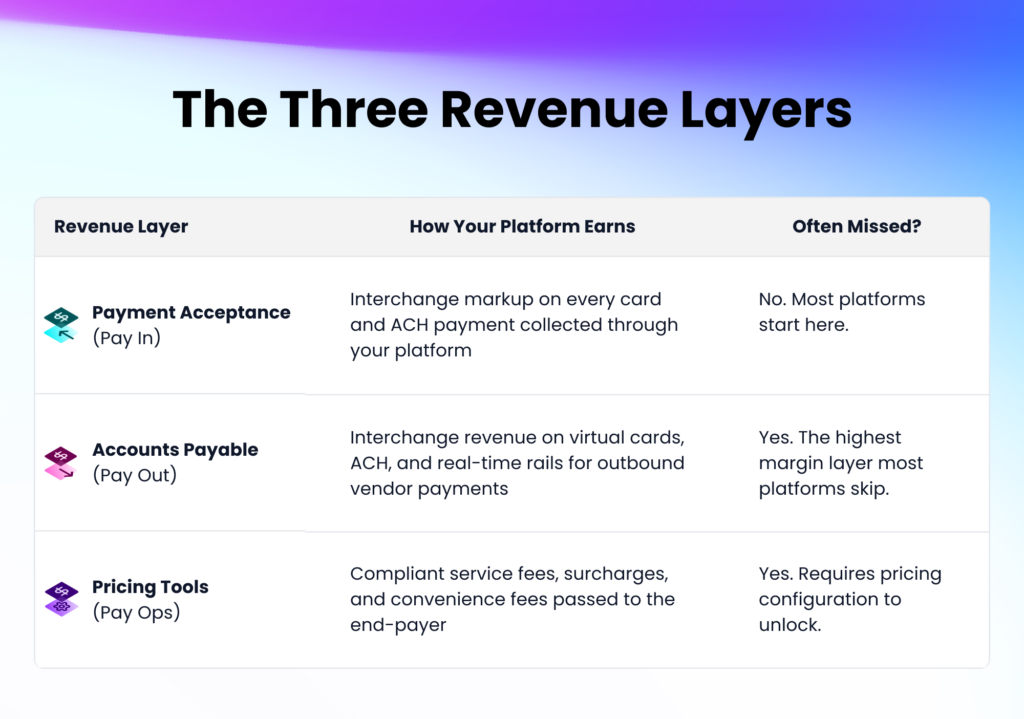
Your platform earns across three layers once you own the infrastructure.

The first is the transaction spread on payment acceptance. Every time a merchant collects a payment, there is a difference between the card network cost at the floor and what the merchant pays to accept it. Your platform retains the margin per transaction through interchange-plus pricing, and passing Level II and Level III data on B2B transactions qualifies those payments for lower interchange categories, widening your margin further.

The second is accounts payable disbursements. When your merchants pay vendors or subcontractors through your platform via virtual cards, real-time rails, or ACH, your platform generates interchange revenue on each outbound payment. This is often the most profitable layer and the one that most SaaS platforms overlook. It also opens the door to a broader embedded fintech stack.The third is the payment experience itself. Merchants pay for capabilities that remove friction in their operations: faster invoice collection, auto-reconciliation, and customer payment portals that cut support overhead.

Here is what the three earning layers look like in practice:

Three-row table listing the payment acceptance, accounts payable, and pricing tools revenue layers with how each earns and whether it is commonly missed.

How can SaaS platforms benefit from payment monetization?

When you own payments, three things change in your business at once: how fast revenue grows, how hard you are to replace, and how you compare to platforms that have not made this move yet.

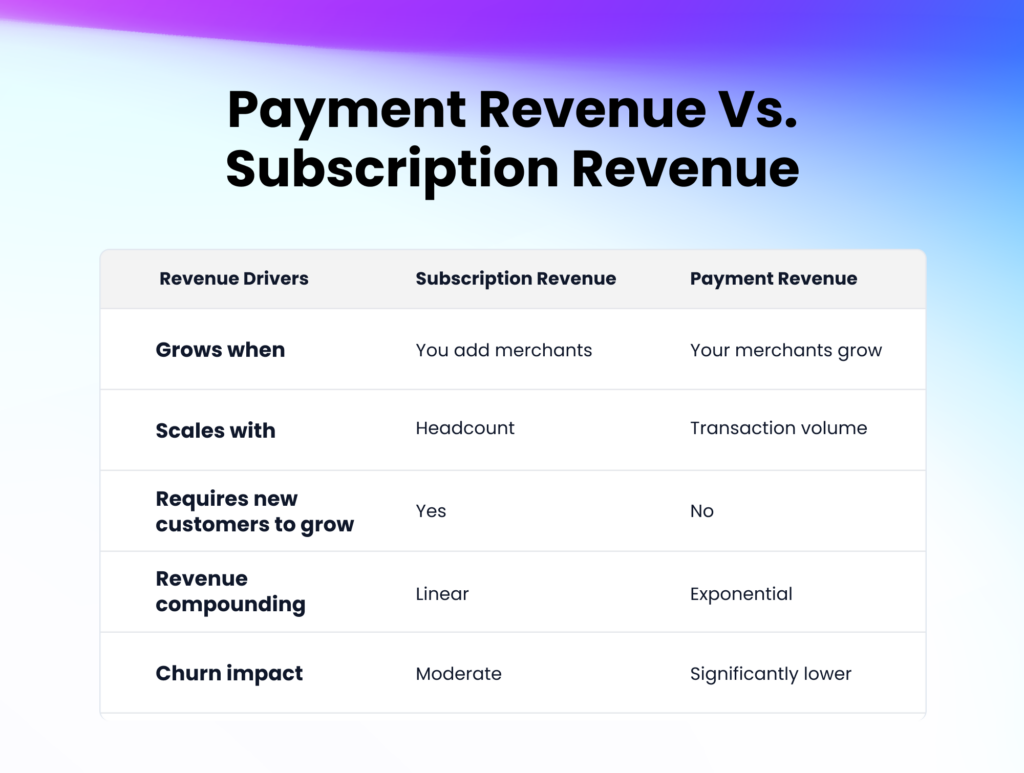
  • Revenue that scales with your merchants. Your subscription revenue grows when you add merchants, whereas your payment revenue grows when your merchants grow. A merchant processing more volume generates more revenue for you automatically, with no upsell and no new contract required.
  • Lower churn, higher retention. Payments embedded in a merchant’s workflow become essential to how they operate. The more transactions they run through your platform, the harder it is to replace you with anything else.
  • A competitive position that is harder to replicate. Shopify’s 2024 annual filing shows its Merchant Solutions segment, which includes payments, shipping, and capital products now accounts for 73% of total revenue.
  • Toast ended 2024 with $4.1 billion in payments and fintech revenue versus $706 million in subscriptions. For both, payments eventually became the business. Subscriptions became the acquisition channel.

The market is moving toward you. The payment volume is already shifting toward software platforms that sit inside merchant workflows. Juniper Research predicts embedded payment transaction volume will hit $2.5 trillion by 2028, a 134% increase from 2024. The platforms moving now are capturing volume that will be structurally difficult to take back later. Waiting is not a neutral decision.

How does payment revenue compare to subscription revenue?

The difference is not just in the margin. Subscription revenue is linear by design, it grows when you add merchants. Payment revenue compounds automatically because it grows when your existing merchants grow. Here is what it looks like side by side.

A revenue model comparison showing payment revenue outperforms subscription revenue on scalability, churn impact, and compounding growth for SaaS platforms.

How can a SaaS platform effectively monetize payments?

Most platforms pick a vendor before they know what they are actually monetizing. That is where things go wrong. Start here instead.

Step 1: Map your payment flows

Start with scope, not technology. Where does money enter your platform, and where does it leave? Which flows are already happening outside your product that merchants would prefer inside it? This tells you how large the opportunity is. If you find more than two payment flows happening outside your product, you have enough volume to start monetizing now.

Step 2: Choose a suitable integration path

Once the scope is clear, the integration choice is straightforward. Full API for teams that want complete control. White-label portal and no-code components for platforms that want to go live with minimal engineering lift. Pick based on your team’s capacity. If you are weighing full PayFac registration against PayFac-as-a-Service, these common myths are worth reading.

Step 3: Build a merchant-oriented pricing model

This is where most of the revenue is won or lost. A blended flat rate is simple but leaves margin behind. Interchange-plus is more transparent and competitive at scale. The right model depends on your vertical and how price-sensitive your merchant base is, and getting it right is easier when your payments infrastructure provider understands the nuances of your industry and can help you price to maximize both adoption and margin

Step 4: Prioritize adoption from day one

Most platforms launch payments and wait for merchants to find them. That is the wrong sequence. Adoption has to be the default, not an option. That means payments surfacing inside the workflow at the moment a merchant creates an invoice or pays a vendor, not buried in a settings tab. Concretely: set your payment flow as the default on merchant onboarding, trigger in-product nudges when a merchant completes a transaction outside your platform, and track activation as a product metric from day one. The right payments infrastructure partner will also come with a point of view on all of this, from the adoption benchmarks that matter in your vertical to the KPIs worth tracking as you scale.

Before-and-after diagram showing a SaaS platform routing payments through a third-party processor versus owning the infrastructure and earning across Pay In, Pay Out, and Pay Ops.

What should you watch out for when monetizing payments for SaaS

Technology is rarely the problem. Most platforms that underperform here make the same three mistakes. All three are avoidable if you know what to look for.

Are there too many vendors or margin leakage?

Every vendor in your payment stack takes a cut. Separate tools for onboarding, acceptance, disbursements, and reporting mean fragmented margin, integration debt, and data you cannot act on. A single API covering payment acceptance, accounts payable, and payment operations keeps those economics where they belong, with your platform.

What’s happening on the outbound side?

If your merchants are paying vendors through external tools, you are leaving revenue on the table and handing retention to another platform. The outbound side is where the next layer of margin lives and where most SaaS platforms have not looked yet.

Does my infrastructure work for my vertical?

Generic payment infrastructure is built for horizontal platforms or use cases, not your merchants’ actual workflows. Property management software needs lockbox collections, field services needs remote deposit capture (RDC) and utilities need ACH billing. The right infrastructure for a vertical SaaS platform is purpose-built for these need-to-pay workflows.

How can Payabli help SaaS platforms monetize payments?

Payabli gives vertical SaaS platforms a single API that unifies payment acceptance (Pay In), accounts payable (Pay Out), and payment operations (Pay Ops), so your platform earns on both sides of money movement without the compliance burden or capital requirements of full PayFac registration.

Platforms that have made this move see it in the numbers. Builder Prime reported a 1,000% increase in payment volume after embedding payments, with payments becoming a core retention driver. Sunbound went from 50% to 90% payor adoption in under a month after moving payments inside the product.

Book a demo to see what the economics look like for your vertical.

Integrated vs. Embedded Payments: What’s Best for Your Vertical SaaS?

Key takeaways:

  • Embedded payments give vertical SaaS platforms full control over merchant onboarding, pricing, branding, and data, whereas integrated payments hand those functions to third parties.
  • Under an integrated model, a platform processing $50 million in annual volume may earn only 5 to 15 basis points in referral fees. In contrast, under embedded payments, the same volume can generate 5 to 10 times more revenue.
  • By using embedded payment strategies, SaaS platforms can retain customers at 2.5 times the rate of traditional payment providers, and their merchants embrace 18% more value-added services (BCG 2025).
  • Vertical SaaS platforms can achieve PayFac-Level economics without full PayFac registration. PayFac-as-a-service provides the same margin control and merchant ownership while eliminating the compliance burden.

In the ever-evolving world of vertical SaaS platforms, choosing the right payment strategy can be a make-or-break decision, not just for platform growth but also for customer experience and monetization. Two terms often used in this conversation are integrated payments and embedded payments. While they may sound similar, the difference is profound, and so are the benefits of getting it right.

In this blog, we’ll break down the distinction between integrated and embedded payments, examine the market data behind each approach, and explain why embedded payments are the gold standard for vertical SaaS platforms looking to scale efficiently and profitably.

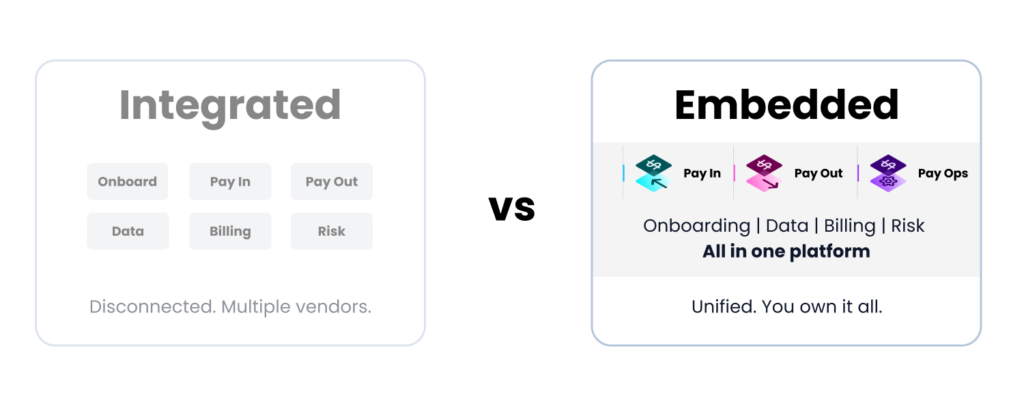
Integrated payments with disconnected components across multiple vendors compared to embedded payments unified under one platform

What are integrated payments?

Integrated payments refer to the approach where a SaaS platform connects to a third-party payment provider (such as Stripe, PayPal, or Authorize.Net) using APIs or plug-ins. While the integration enables payment functionality, the actual experience, like merchant onboarding, transaction monitoring, or settlement, is still handled largely outside of your platform.

SaaS company’s control over the pricing, user experience, and monetization is limited by this model. Software platforms now manage 60-70% of their clients’ payment processing contracts according to a 2025 BCG report on merchant services. Platforms using integrated payment models often give up this control to the third-party providers, along with the linked revenue.

What are embedded payments?

Embedded payments go a step further by deeply integrating the entire payment experience within the SaaS platform. From merchant onboarding and KYC, to accepting payments, managing payouts, and delivering insights, everything happens natively in the software interface.

Fully embedded payments within your platform mean that merchants onboard, transact, and access real-time reporting without ever leaving your software. This ensures a seamless, consistent experience that feels like a natural part of your product, not an external add-on.

This model is often powered by becoming a Payment Facilitator (PayFac) or by partnering with a PayFac-as-a-Service provider. 

The financials for embedding payments are well documented. According to Bain & Company, the embedded finance revenue is projected to increase from $21 billion in 2021 to around $51 billion by 2026. The embedded payment market alone reached $24.7 billion in 2024 and is growing at a 30.3% CAGR through 2034.

Integrated vs. embedded payments: A side-by-side comparison

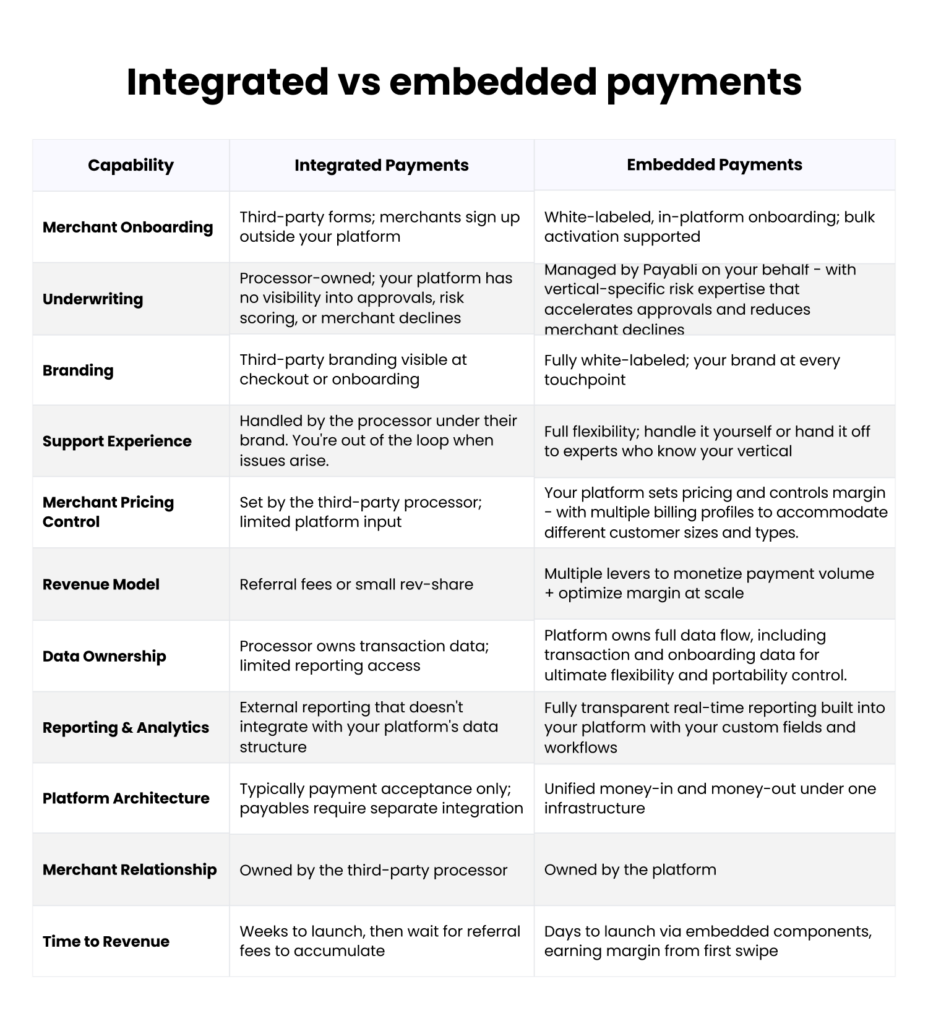
The significant difference between the two models extends across onboarding, revenue, data ownership, branding, and compliance. The table below summarizes how each approach performs on capabilities that matter most to platform administrators.

Integrated payments vs. embedded payments comparison across onboarding, branding, pricing, revenue, data ownership, compliance, and time to launch.

For a practical walkthrough of what it takes to go live with embedded payments, see Payabli’s Embedded Payments Launch Checklist.

Why do embedded payments win on user experience?

For vertical SaaS platforms, user experience is everything. Embedded payments dramatically enhance the merchant journey and unlock new business value in ways integrated payments simply can’t.

1. Frictionless onboarding

Say goodbye to third-party forms and redirection. Merchants can sign up and start accepting payments right inside your platform, often within minutes. Payabli’s Creator tool enables platforms to apply branded onboarding without any coding, further reducing time to first transaction. 

2. Unified UI and experience

The payment flow stays consistent with your platform’s design. This creates a branded, trustworthy experience for your users.

3. Faster time-to-revenue

While integrated options may involve multi-day approval processes, embedded payments often enable instant and/or bulk onboarding and activation, meaning your users start transacting sooner. This speed directly translates to faster payment volume growth for platforms serving high-volume verticals.

4. Deeper data visibility

With embedded payments, your platform owns the entire data flow, transaction history, user behavior, and payout activity, which means better analytics and smarter customer engagement.

5. New revenue streams

Rather than handing over valuable payment margins to third parties, you capture a share of the transaction revenue. This high-margin income can transform your SaaS business model. According to Andreessen Horowitz, revenue per user can be increased 2 to 5 times by adding embedded payments.

6. Streamlined compliance (with the right partner)

PayFac-as-a-Service solutions help you deliver a native experience without taking on the full regulatory or administrative burden of being a registered PayFac yourself.

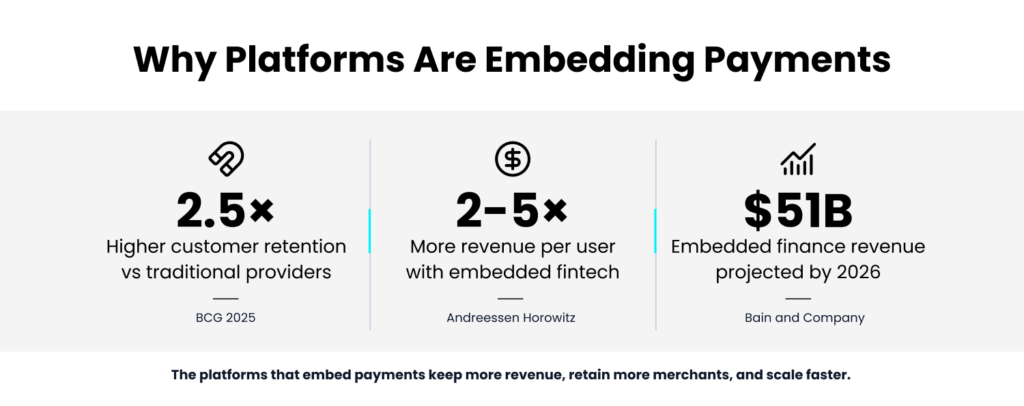
Three key embedded payments statistics: 2.5x higher customer retention, 2 to 5x more revenue per user, and $51 billion in projected embedded finance revenue by 2026

How to evaluate your payment model

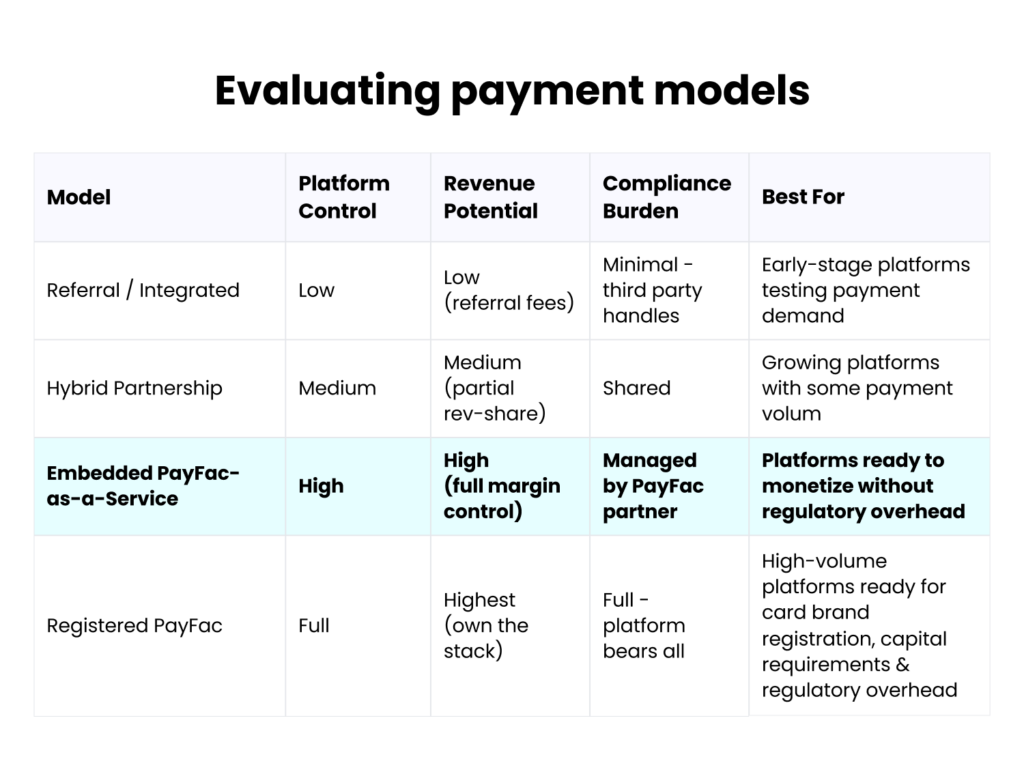
The perfect payment model depends on your platform’s technical resources, stage, and growth goals. Not every platform is prepared for full PayFac registration, but most can benefit from PayFac-as-a-Service immediately. The table below outlines the four primary models and what each requires.

 Comparison table showing four embedded payments models: Referral/Integrated, Hybrid Partnership, PayFac-as-a-Service, and Registered PayFac, evaluated across platform control, revenue potential, compliance burden, and best-fit use case.

What to look for in an embedded payments provider

If you’re ready to embed payments into your SaaS platform, the provider you choose will have a massive impact on both your product experience and your bottom line. Here are four key things to look for:

1. Unified Pay In and Pay Out capabilities

A common limitation among many embedded payment providers is the inability to support both payments and disbursements under one roof. This can create friction when trying to manage sub-merchants, service providers, or vendor payouts. Choose a provider that bridges both sides of the money movement, ensuring faster settlement, seamless fund distribution, and better cash flow control. The ability to earn revenue on both inbound and outbound payment flows, including virtual card rebates on vendor payouts, is what distinguishes a payments feature from a payments business.

2. Flexible integration options

Your development team shouldn’t have to force-fit your platform into rigid SDKs or templated flows. Look for providers that offer modern, modular APIs, webhooks, and event-driven architecture, and clear documentation and sandbox environments. This allows you to tailor the payment experience to your platform’s design and business logic.

3. Hands-on, expert support

Payments can be complex, but your journey shouldn’t be. The right provider offers proactive, strategic guidance from discovery to go-live, and everything in between. That includes technical integration support, merchant onboarding optimization, compliance and risk workflows, and ongoing product and go-to-market strategy. Unlike most providers, the right partner will also offer merchant-level support.

Beyond launch, you should expect responsive, hands-on support from experts who understand your industry. The right partner will help you and your customers resolve issues quickly, optimize operations, and provide guidance tailored to your vertical, whether you’re serving contractors, gyms, law firms, or property managers.

4. Cost and pricing transparency

A strong payment partner doesn’t just present pricing, they help you understand it and turn it into a strategic revenue stream. Look for transparent rates and no hidden fees, flexible monetization options, simple easy-to-read billing, tailored pricing strategies by vertical, flexible pricing structures, and granular monthly statements to optimize margin at scale.

For vertical SaaS platforms, payments are more than a back-end utility, they’re a strategic lever for growth, retention, and monetization. While integrated payments may offer a quick start, embedded payments create long-term value through a smoother user experience, stronger brand ownership, and deeper monetization opportunities.

Choosing the right partner is just as important as choosing the right model. With the right embedded payments provider, your SaaS platform won’t just process payments, it will own them.

From integrated payments to a payments business

Most vertical SaaS platforms started with an integrated payment model because it was the fastest path to offering payments. But as your merchant base grows, the gap between what integrated payments deliver and what embedded payments unlock becomes harder to ignore: more revenue per transaction, full brand ownership, and a merchant relationship you control. See how the two models stack up in our full comparison table above.

Payabli helps platforms make that transition. Whether you are moving off a referral model, replacing a fragmented multi-vendor setup, or embedding payments for the first time, Payabli’s unified Pay In, Pay Out, and Pay Ops infrastructure gets you live in weeks with PayFac-Level economics.

Book a demo to see how platforms like Sunbound made the switch.

What Good Underwriting Looks Like for Vertical SaaS Platforms

By Cathy Livingston | Compliance, Risk & Underwriting Specialist, Payabli

I’ve spent nearly three decades in financial risk – starting in personal lending, moving into payment processing about ten years ago. The shift changed everything. Instead of evaluating individual consumers, I’m now evaluating businesses and their financials, transaction patterns, and risk profile within a payments ecosystem.

If you’re a vertical SaaS company bringing payments to your customers, here’s what good underwriting actually looks like – and why it matters more than most platforms realize.

Underwriting Isn’t a Bottleneck. It’s a Foundation.

The ‘underwriting is a bottleneck’ conversation comes up a lot, and I understand it. But here’s the reframe: a bottleneck holds back everything. Underwriting, when it’s done right, holds back the right things – the merchants who would have generated chargebacks, the fraud that would have hit your platform, the risk that would have slowed your growth far more than any approval process ever could. And with AI-powered risk tools now part of the equation, the gap between thorough and fast is closing faster than most platforms realize.

What I wish more people understood is that good underwriting protects our SaaS partners just as much as it protects Payabli. If a merchant is approved for limits they can’t sustain, or if there are risk factors we didn’t catch upfront, it’s the SaaS platform who feels that downstream. Chargebacks, disputes, fraud exposure – those land on everyone. When underwriting is done well, it’s almost invisible. Everything just works.

Vertical SaaS Changes the Equation

Here’s what makes underwriting for vertical SaaS platforms different: you’re not bringing one merchant to a payments processor. You’re bringing hundreds or thousands of merchants, all operating in the same industry vertical.

Every vertical has its own financial fingerprint, and you have to know what normal looks like before you can spot what’s off. A roofing company might show very low deposit activity in January and February – that’s not a red flag, that’s winter. A childcare center is going to show steady, predictable monthly deposits that look very different from a construction contractor’s project-based cash flow. Understanding that distinction is what separates good underwriting from slow underwriting.

At Payabli, our SaaS partners serve specific verticals, so over time we develop real fluency in what their merchant portfolios look like. That context makes an underwriter a faster, more confident reviewer – and a better resource for the SaaS platform when they have questions about a decision. 

How a Merchant Application is Evaluated 

When a merchant application comes through your platform, here’s what I’m evaluating:

Business owner and business information.

Who is behind this business, how is it structured, and what industry are they operating in? Certain business types carry higher inherent fraud or chargeback risk, and ownership details can surface red flags early, before even getting to the financials. This context helps shape every other part of the review.

Bank statements and processing history. 

These aren’t always required – but when a merchant’s volume request needs additional support, this context can help tell the real story of a business. Average balances, deposit consistency, how volume has trended. If a merchant is requesting a $500K monthly processing cap but their bank statements show $80K in average monthly revenue, that gap needs an explanation.

Consistency across documents. 

Does the business description match the financials? Does the requested volume make sense for the size of the operation? Red flags in underwriting are often about inconsistency more than any single data point.

Fraud indicators. 

In payment processing, underwriting is often the first line of defense – we’re reviewing these applications before a merchant ever processes a transaction. Catching something early protects your platform, your merchants, and the entire ecosystem you’ve built.

Where AI Is Changing the Underwriting Equation

At Payabli, we use AI to help review information-dense documents (think: bank statements, processing history, financial statements) and run deeper analytics than would be practical manually. It surfaces what needs attention faster, so the underwriting team can spend more time on the judgment calls that actually require experience.

Because here’s what AI can’t do: interpret context. It might flag irregular deposit activity – but a person who knows the industry understands whether that’s a real concern or just seasonality. Automation makes us faster and more thorough. It doesn’t replace knowing what you’re looking at. For vertical SaaS platforms, that combination means faster approvals for clean merchants and earlier intervention on the ones that need a closer look. The bottleneck gets smaller. The diligence doesn’t.

The Bottom Line

The best partner relationships are ones with real back-and-forth – they understand what we need to make decisions, and we understand the merchants they’re bringing on. SaaS platforms who invest in understanding the underwriting process see fewer follow-up requests and smoother onboarding overall.

Payabli wants merchants to succeed – and underwriting is one of the first ways we set them up to do exactly that. 

Introduction to Embedded B2B Payments

Key Takeaways:

  • Embedded B2B payments enables vertical SaaS platforms to bring the entire payment experience natively inside their product, capturing economics on both sides of money movement without full PayFac registration.
  • The embedded B2B payments market is projected to grow nearly fourfold by 2030, shaped by demand for integrated workflows and the decline of paper-based payments.
  • The fastest-growing B2B payment method is virtual cards, with transaction volume projected to grow from $3 trillion in 2024 to $11 trillion by 2028, yet they represent only 2% of accounts payable transactions today.
  • Embedding Pay In and Pay Out under a single unified API enables vertical SaaS platforms to capture both sides of money movement while building deeper customer stickiness.

B2B transactions still rely on manual invoicing, paper checks, and disconnected systems. More than half of all B2B invoices are currently overdue, and the downstream effects (reconciliation failures, delayed cash flow, and strained supplier relationships) are symptoms of the same root problem: payments that operate outside the software where business actually happens.

Vertical SaaS platforms that embed payment acceptance (Pay In) and accounts payable (Pay Out) directly into their product don’t just add a feature. They remove the friction that’s costing their customers real money and unlock a revenue stream that scales with every transaction.

Embedded B2B payments address this by integrating payment capabilities directly into the software platforms businesses already rely on. Instead of toggling between third-party payment tools, portals, and accounting systems, payments happen inside the workflow. This blog covers what embedded B2B payments are, why the market is accelerating, and what to evaluate in an infrastructure partner.

What Are Embedded B2B Payments?

Embedded B2B payments refers to bringing the entire payment experience natively inside the software platforms businesses already use. Through a PayFac-as-a-Service model, your platform captures the economics and controls the experience end to end, with no full PayFac registration required. Rather than context-switching to separate tools, all money movement happens inside the workflow, under your brand, on your terms.

For vertical SaaS platforms, embedded payments are often the foundation of a broader financial services strategy that can expand to include lending, insurance, or banking services over time.

When a property management company logs into its platform to collect HOA dues and then opens a separate banking portal to pay a vendor, those are disconnected B2B payments. With embedded B2B payments, both transactions happen inside the same platform, with the invoice, reconciliation, and payment all connected.

When working with the right payment infrastructure provider, embedded B2B payments can cover both sides of money movement for your platform. On the acceptance side (Pay In), merchants collect via cards, ACH, checks, and digital wallets. On the disbursements side (Pay Out), they pay vendors through ACH, wire transfers, virtual cards, and real-time payments (RTP), generating interchange revenue on every vendor payment. Pay Ops, the operational layer connecting both, handles underwriting, risk management, reconciliation, reporting, and compliance across the full payment lifecycle.
The key distinction in B2B payment workflows is that transactions involve invoices with multi-party approvals, large dollar amounts, payment terms, and compliance obligations that require purpose-built infrastructure to manage.

To explore how vertical SaaS platforms are layering additional financial products on top of payments, see Beyond Embedded Payments.

Why embedded B2B payments are one of the highest-value opportunities for vertical software platforms

Embedding payments isn’t just a feature add. It’s a revenue stream that grows with every transaction processed on your platform. Larger transactions, longer customer relationships, and deeper workflows makes embedded B2B payments one of the most significant monetization opportunities in vertical software platforms today.

  • New revenue streams on both sides of the money movement. Embedded B2B payments unlock transaction-based revenue across Pay In and Pay Out, two channels most platforms leave on the table. On the Pay In side, every card payment, ACH transfer, or digitized check collected through your platform generates transaction revenue. On the Pay Out side, virtual cards are among the highest-margin disbursement methods available, generating interchange revenue on every vendor payment, often exceeding 100 basis points. Virtual cards represent just 2% of accounts payable transactions today, while 80% of buyers prefer them (Tearsheet). That gap is the opportunity.
  • Larger transactions mean more revenue per payment. B2B transactions routinely run into thousands or tens of thousands of dollars. A platform processing a $50,000 vendor payment captures significantly more per transaction than one handling a lower-value payment. The underwriting and risk models that support those larger amounts also deepens the value your platform delivers, giving businesses meaningful financial controls built directly into their workflow.
  • Better data makes your platform stickier. B2B payments generate rich transaction data: remittance details, invoice matches, ledger entries, and purchase order records. Surface that through reconciliation feeds and Level II/III transaction support, and your platform becomes the financial system of record your customers won’t switch away from.
  • Faster onboarding and simplified compliance. The right embedded payment infrastructure provider handles KYB verification, underwriting, and risk monitoring natively, so your team can focus on the product and your customers can start transacting quickly, without the friction of managing it separately.
  • More control over the customer experience. When payments live inside your platform, you control the full experience. Branded payment flows, configurable payment terms, automated reminders, and real-time reporting all happen inside your product, not in a third-party portal your customers have to navigate.

The Market Opportunity: Why Now?

The market is massive, underpenetrated, and moving fast. Embedded B2B payments are growing at a 25% CAGR, projected to reach $15.6 trillion by 2030 (Edgar, Dunn & Company). According to PYMNTS Intelligence, 62% of businesses now expect ERP integration for their accounts payable solutions, and 36% of executives identify adopting in-platform payment capabilities as a top priority for staying competitive. For vertical software platforms, that pressure is an opening: businesses are actively consolidating financial operations inside the tools they already use.

The shift away from legacy payment methods is accelerating. In September 2025, the U.S. Treasury moved away from paper checks for most disbursements, and similar digital-first mandates are emerging globally. Virtual cards and real-time payments are replacing manual AP workflows, and AP automation adoption is driving disbursement volume onto higher-margin rails.

A longer-term force is also taking shape: agentic fintech. As AI agents execute financial workflows autonomously, the platforms that have already embedded payments will be positioned to absorb that automation layer naturally. Payments won’t just be a feature your customers use. They’ll be a function AI operates on their behalf, inside your platform.

Vertical SaaS platforms that move now, embedding Pay In, Pay Out, and Pay Ops under a single unified API, are building payment businesses, not just adding features.

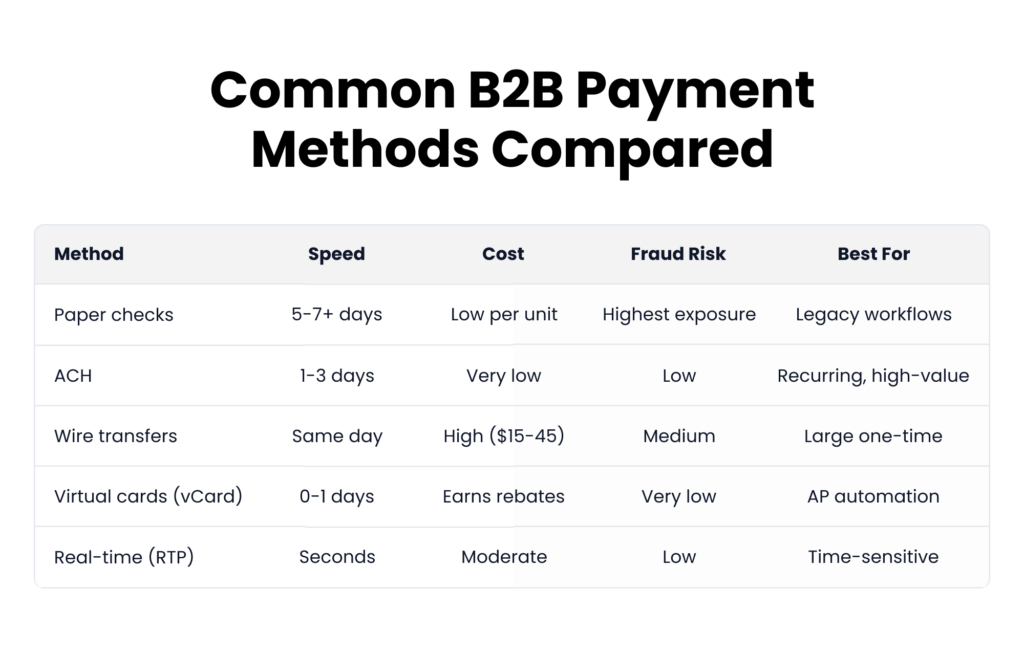
Comparison table of five common B2B payment methods including paper checks, ACH, wire transfers, virtual cards, and real-time payments, evaluated across speed, cost, fraud risk, and best use case.

What to evaluate in a B2B Payments infrastructure partner

B2B embedded payments require capabilities that go well beyond standard payment processing. The right partner should be purpose-built for these workflows.

Vertical-specific payments expertise

Payment workflows aren’t generic, and neither is the infrastructure that should support them. A construction platform managing progress billing and subcontractor disbursements has fundamentally different requirements than a property management platform collecting rent and HOA dues, or a healthcare platform navigating patient billing and insurance reconciliation.Your infrastructure partner should be purpose-built for vertical software, not a horizontal processor retrofitting generic tools to your use case.

Integration that meets your engineering team where they are

Embedding payments should accelerate your product roadmap, not slow it down, and the right partner gives you optionality based on where you are in your payments journey. The right partner supports a crawl, walk, run approach: launch with pre-built tools, embed with configurable components, then build a fully custom experience when you’re ready. And if you’re starting with Pay In but want to layer in Pay Out down the road, that expansion should be straightforward, not a separate conversation.

Compliance built for B2B payment workflows, not bolted on after

B2B payments carry requirements that go well beyond standard PCI DSS and NACHA obligations. KYB verification for onboarding multi-entity merchants, positive pay for check fraud prevention, and Level II/III data submission for interchange optimization are baseline B2B expectations, not edge cases. Look for a partner that handles these natively and engages directly on underwriting, not one that hands you a questionnaire and walks away. That distinction keeps your engineering team focused on your product roadmap and your compliance posture intact.

Dedicated support and implementation partnership. 

The implementation phase is where most embedded payments programs succeed or stall. The right partner assigns a dedicated team, not a ticketing queue, from onboarding through launch and beyond. The right partner understands your platform before integration begins, not just after something breaks. Proactive monitoring, clear escalation paths, and a partner invested in your long-term success, not just your go-live date, are the markers of a provider worth trusting.

Merchant adoption, conversion, and monetization strategies.

Embedding payment capabilities is only the beginning. Revenue is directly tied to how many customers activate and how deeply they engage. Look for a partner with proven merchant adoption playbooks and launch checklists, friction-reducing onboarding flows, and in-platform prompts that drive activation at the right moment. The right partner works alongside you to increase payment volume and deepen engagement across your customer base, so your payments program compounds as your platform grows.

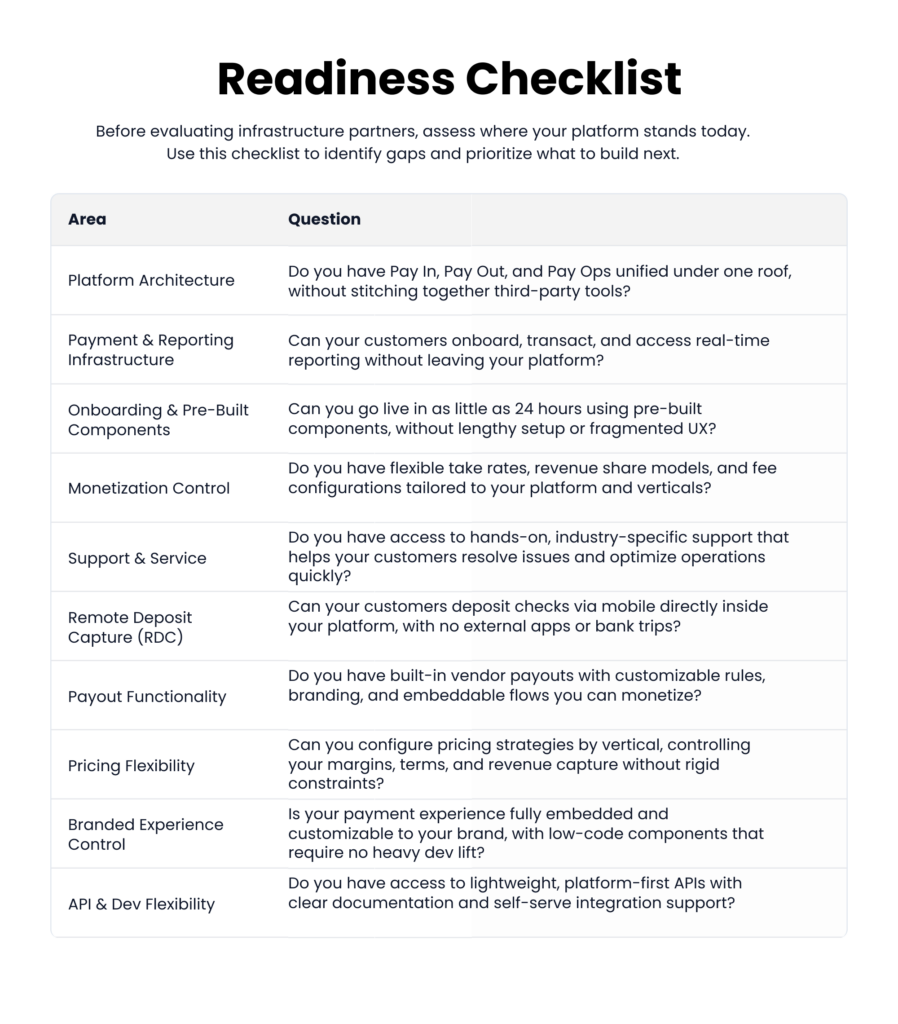
A self-assessment table for vertical SaaS platforms covering ten key areas of payment infrastructure readiness, from platform architecture and monetization control to branded experience and API flexibility, helping teams identify gaps before evaluating an embedded payments partner.

From Payment Features to a B2B Payments Business

Platforms that embed B2B payments capture margin on both sides of every transaction, build a revenue stream that scales with their software, and deepen the merchant relationships that drive long-term retention. The opportunity ahead is significantly larger than what has already been captured.

Intelligence across your entire payments stack

Payabli is the Intelligent Fintech Operating System for Software Platforms. That intelligence runs across the entire stack — Pay In, Pay Out, Pay Ops — powering real-time answers, automated workflows, and actionable insights for every vertical and every business model.

Payabli works with vertical SaaS platforms across property management, HOA property management, field services, construction, education, healthcare, nonprofit, legal, and government to design and launch B2B payment strategies specific to their vertical. If you’re exploring how to embed and monetize B2B payments into your platform, book a demo today.

Embedding Payments in SaaS: Best Practices

Key Takeaways:

  • The best practice to embed payments in SaaS is to find an infrastructure partner that unifies payment acceptance, disbursements, and operations within a single API, with seamless merchant onboarding, white-labeled user experience, and a scalable pricing strategy.
  • The three essential decisions include merchant onboarding flow, integration model (API, no-code, or white-label), and the pricing model. Missteps in any of these would delay adoption.
  • White-labeling the entire payment workflow keeps merchants inside your platform, resulting in reduced churn rate and driving higher payment adoption rates.
  • Payment operations (onboarding, compliance, risk, billing) are just as important as the payment technology; however, 70% of the platforms still treat payments as a commodity. 
  • SaaS platforms that combine acceptance, disbursement, and operations under a single API eradicate vendor fragmentation and go live in weeks instead of quarters. 

Embedding payments in SaaS is one of the most consequential decisions a software platform can make — and one of the most misunderstood. The technical lift of adding a payments layer is only part of the equation; the real complexity lies in architecting an experience that drives merchant adoption, scales with your business, and captures the full revenue potential payments can unlock. Platforms that treat embedded payments as a feature rather than a strategic capability often find themselves rebuilding from scratch. Getting it right the first time requires a clear-eyed understanding of where the pitfalls are — and how to avoid them.

Meanwhile, platforms that follow proven implementation strategies are doubling their payments revenue within three months of launch (EY-Parthenon). The gap between doing it and doing it well is worth millions, as it is projected that with embedded payments transaction value would surpass $2.5 trillion by 2028 (Juniper Research). This guide covers eight best practices that distinguish platforms generating real payment revenue from those still figuring it out.

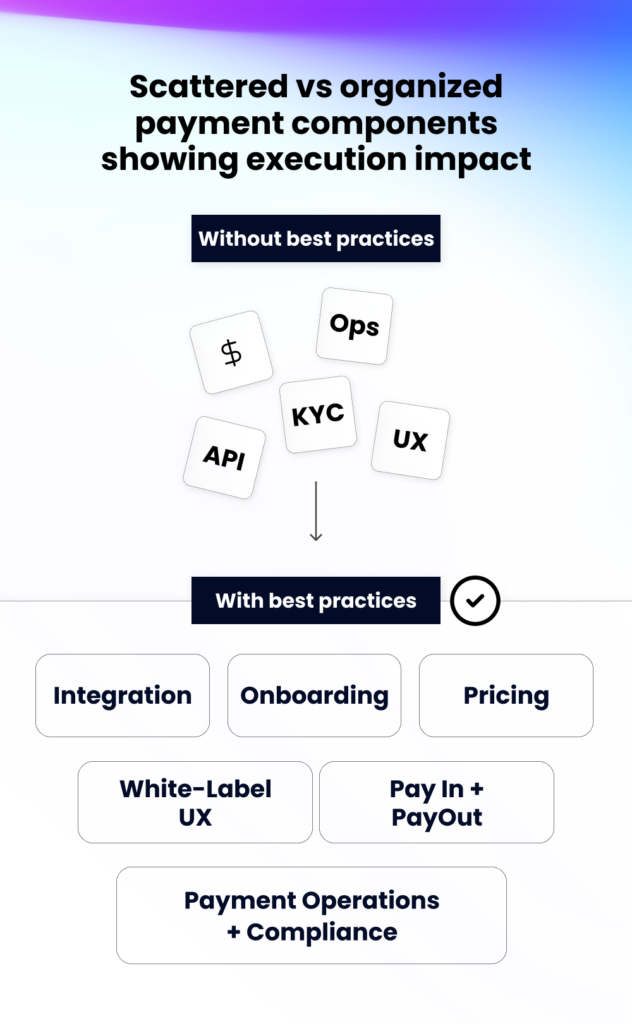
Scattered vs organized payment components showing execution impact

1. Choose the Right Integration Approach

There are three paths to embedding payments, each with different tradeoffs around control, speed, and engineering lift.

  • Pre-Built Payments Portal: The fastest entry point. Payabli’s ready-made portal and hosted tools let you start accepting and managing payments without building much yourself. Payments are functional from day one, with white-label opportunities to keep it on-brand.
  • Embedded Components: Pre-built JavaScript UI modules (payment forms, boarding links, merchant dashboards) that drop into your platform with minimal development effort. Launch in weeks with full functionality and CSS-level branding control. This is where most SaaS platforms land when they want payments inside their product without heavy infrastructure work.
  • Full API: Complete control over every screen, data point, and workflow. The right choice for platforms with dedicated engineering teams that want a fully tailored payment experience. It takes longer to build, but you own every interaction.

Partners shouldn’t have to start at the most complex integration. Payabli supports a natural progression: launch quickly with hosted tools, embed payments with configurable components, then build a fully custom experience when you’re ready.

2. Make Merchant Onboarding Frictionless

The first experience your customers will have with payments on your platform is merchant onboarding. If the process feels disconnected from your product or adds unnecessary friction, adoption can stall before it even begins.

The most effective onboarding workflows share a few core principles. Use existing platform data — tax ID, business name, address — to pre-fill the merchant application, so customers aren’t re-entering information they’ve already given you. Keep the form completable in a single session. Deliver the experience through a white-labeled boarding workflow so merchants stay within your platform from start to finish. Leverage automated KYC/KYB verification to remove manual bottlenecks, and surface real-time application status updates so merchants always know where they stand — reducing drop-off and accelerating activation.

According to BCG, a higher activation and retention rate is observed on platforms that have seamless onboarding, as it reduces friction in merchant experience.

3. White-label Everything

The payment experience should feel native to your platform. For you and for every merchant you serve. When a merchant onboards, submits a payment, checks a dashboard, or receives a receipt, that interaction is a direct reflection of your product. Friction at any one of those touchpoints isn’t just a UX problem, it’s a retention risk. 

Every step should carry your brand: checkout pages, payment forms, reporting dashboards, onboarding applications, transactional receipts, email notifications, and settlement communications. When merchants see consistent branding across every interaction, payments feel like a core feature of your platform — not a third-party service bolted on. That consistency builds trust, drives adoption, and reduces churn.

With more than 60% of vertical SaaS platforms already embedding payments (EY-Parthenon), your merchants expect this level of consistency. The bar for what “native” looks like is only rising.

4. Cover Both Sides of Money Movement 

Payment acceptance (Pay In) is table stakes for most platforms, but merchants also send money, like paying vendors, suppliers and subcontractors. This is the account payables (Pay Out) option, and it represents a substantial revenue opportunity. 

For example, in a construction management platform, a general contractor collects payments from the property owners (Pay In) and then is required to pay plumbers, electricians, and other suppliers (Pay Out). Similarly, in property management, a platform’s client collects rent from tenants, then pays utility companies, maintenance vendors, and property owners. The platforms that only monetize one side of payments are leaving potential revenue on the table, as both sides of the payment carry a margin. 

The best practice is to choose a platform with a single unified API offering both acceptance and disbursements. A unified view of all money movement across your platform is enabled, without the need to manage two separate vendors. When Pay In and Pay Out share the same reconciliation, reporting, and billing layer, the operational friction reduces critically.

5. Don’t Ignore Payment Operations

Payment operations are the backbone of a scalable payments strategy — and the most underestimated part of it. Getting live is the easy part. Pay Ops is what ensures merchant underwriting, chargeback management, risk and fraud monitoring, compliance reporting, pricing and billing configuration, and funding and settlement management run efficiently — freeing your team to focus on growth instead of back-office overhead.

Most software platforms treat payments as a utility. The ones that treat it as a strategic lever — investing in the operational layer, not just processing — are the ones that drive retention, unlock new revenue, and build durable competitive advantage.

The takeaway: choose a partner that offers operational depth alongside a payments API, not just processing capability. Onboarding templates, billing engines, risk controls, and reporting dashboards are just as important as accepting a card payment.

6. Offer Multiple Payment Methods

Your merchant’s customers expect multiple payment options at checkout. At minimum, platforms should provide support for credit and debit cards (Visa, Mastercard, Discover, Amex), bank transfer and ACH, digital wallets (Google Pay, Apple Pay), SMS pay links, and checks, such as RDC (remote deposit check capture) for verticals that need it. 

Your payment methods should match your vertical. A property management platform needs ACH and remote deposit check capture — how most homeowners and tenants prefer to pay. An education platform benefits from recurring billing and flexible payment schedules. A field service platform needs Tap to Pay and digital wallet support for fast, on-site transactions. And regardless of vertical, any modern payment stack should include digital wallets: Juniper Research cites “global digital wallet users will exceed 5.2 billion by 2026, growing by 35% between 2025 and 2030.”

7. Build a Pricing Strategy That Scales

Instead of simply passing through processing costs, treat payments as a standalone P&L — built to optimize operations, maximize revenue, and scale your business.

Pay In: Your pricing model determines how much of the payments opportunity you capture. IC+, tiered, flat rate, or zero-cost processing — configure the right model for the right customer across your entire portfolio.

Pay Out: Every vendor payment your platform sends is a transaction — and every transaction is a chance to capture margin. Virtual cards generate interchange. ACH can carry per-transaction fees. Checks have issuance economics. Platforms that monetize only one side of money movement leave revenue on the table.

The opportunity is significant. Edgar, Dunn & Company estimates embedded B2B payments will grow from $4.1 trillion in 2024 to approximately $15.6 trillion by 2030 — nearly a fourfold increase at a 25% CAGR. The pricing decisions you make today will directly shape your margin at that scale.

8. Plan for Compliance from Day One

Compliance is a significant part of any payment platform, not a secondary consideration. PCI DSS (Payment Card Industry Data Security Standard) for card data security, NACHA rules for ACH transactions, KYC/KYB verification for merchant identity, and state-level money transmitter regulations are some of the requirements for handling payments.

The best practice would be to work with an infrastructure partner that handles compliance as a part of the platform itself. Encryption, tokenization, and fraud detection should be part of the backbone of the platform. With the right partner, engineering overheads, risk exposure, and ongoing audit costs could be avoided, which are usually faced by platforms trying to manage PCI scope internally. 

Build Your Embedded Payments Strategy with Payabli

Payabli’s unified API consists of Pay In, Pay Out, and Pay Ops, providing vertical SaaS companies with a single integration for acceptance, disbursements, and operations. With white-labeled onboarding, transparent revenue sharing, and no-code components, platforms can go live within weeks rather than quarters.
100+ vertical SaaS platforms and 60,000+ merchants across education, fitness, construction, property management, field service and government are powered by Payabli. Whether you are initially launching payments or replacing a legacy integration, Payabli’s team can help you build a custom payment strategy for your vertical.

Talk to Payabli’s team and see how embedded payments can work for your platform.

GDPR Compliance in Payment Processing: What SaaS Platforms Need to Know


Written by: Emilio Sepulveda, Director of Engineering @ Payabli

The General Data Protection Regulation (GDPR) is the European Union’s landmark data privacy law, and one of the strictest in the world. It sets comprehensive standards for how organizations collect, process, store, and protect the personal data of EU residents. But GDPR’s influence extends far beyond Europe.

Although the United States has no single federal privacy law of comparable scope, 20 states have enacted comprehensive privacy laws, many of which draw directly from GDPR principles. That growing patchwork of regulation, combined with increasing enterprise buyer expectations, has made GDPR the de facto benchmark that US-based SaaS companies follow when building data privacy programs.

We’re proud to announce that Payabli is GDPR compliant. The supporting documentation is available in our Trust Center.

The cost of getting data privacy wrong

Non-compliance with data protection regulations is not just a legal risk. It is a financial one. According to the CMS GDPR Enforcement Tracker (2025), European data protection authorities have issued a total of 2,245 fines since GDPR took effect, totaling approximately €5.65 billion. That figure grew by over €1.17 billion in just the past year, with the average fine across all countries reaching €2.36 million.

The financial exposure goes beyond regulatory penalties. IBM’s Cost of a Data Breach Report (2025) found that the global average cost of a data breach reached $4.44 million, with US organizations facing a record $10.22 million per breach. Customer PII was the most frequently compromised data type, involved in 53% of breaches studied.

And the reputational damage may be even harder to recover from. According to the same IBM report, nearly two-thirds of breached organizations are still recovering more than 100 days after an incident. For SaaS platforms that embed payment processing, where sensitive financial and personal information flows constantly, a gap in data protection can erode trust fast.

Why GDPR compliance matters for SaaS platforms

When you embed a payments processor into your platform, you inherit its data practices. If your processor cannot demonstrate how personal data is collected, stored, and protected, that liability flows upstream to you.

This is not a theoretical concern. According to DLA Piper’s 2026 survey, European regulators issued approximately €1.2 billion in GDPR fines in 2025, with aggregate fines since 2018 now reaching €7.1 billion. Meanwhile, breach notifications surged 22% to an average of 443 per day. For SaaS companies, compliance is no longer optional. It is a baseline procurement requirement.

Enterprise legal teams now routinely require proof of GDPR compliance, including completed data processing agreements, SOC 2 reports, and documented security controls, before signing contracts. Recent research shows that 99% of organizations consider external privacy certifications important when choosing a vendor.

That’s why at Payabli, we consistently map data from ingestion through storage, tracing where personal information enters our environment, how it flows across systems, what controls protect it, and the legal basis that allows us to process it. The result is more than a compliance checkbox: it’s a genuine understanding of what we collect, why we collect it, and how we safeguard it.

When a regulator, auditor, or enterprise customer asks how you handle personal data, your payments layer cannot be a gap in your answer.

What GDPR means for your platform’s customers

GDPR gives individuals specific, enforceable rights over their personal data. One of the most important is the Data Subject Access Request (DSAR). A DSAR is a formal request from an individual asking:

  • What personal data do you hold about me?
  • How are you using it?
  • Can I get a copy?
  • Can I correct or delete it?

These requests are legally time-bound and must be handled carefully and consistently. Organizations must respond within 30 days under GDPR, and the demand for Data Protection Officers (DPOs) has surged more than 700% since the regulation took effect.

Payabli is built to help platforms support and manage these requests, so that when your merchants or their customers exercise their rights, you have the infrastructure and documentation in place to respond with confidence.

The US regulatory landscape is catching up

While GDPR remains the global standard, the US privacy landscape is evolving rapidly. Twenty states now have comprehensive privacy laws, with eight new laws becoming enforceable in 2025 alone, nearly doubling the number of states with active statutes. Maryland and Minnesota, in particular, introduced obligations that go further than many existing frameworks.

For SaaS platforms operating across state lines, especially those in PCI DSS-regulated industries like payments, this patchwork creates real complexity. Building to a GDPR-level standard today positions your platform to meet not only European requirements but the growing mosaic of US state regulations as well.

How Payabli embeds privacy into our infrastructure

GDPR compliance doesn’t live in a single document or team. At Payabli, privacy by design is integrated into how we build and operate:

  • Role-based access controls limit who can access personal data and when.
  • Recurring access reviews ensure permissions stay accurate over time.
  • Documented processing activities create a clear record of what we do and why.
  • Defined retention and deletion standards mean data doesn’t linger longer than it should.

These are not annual audit exercises. They are operational practices that run continuously, reflecting the principle that compliance is sustained through execution, oversight, and accountability.

This matters especially in payment processing, where sensitive financial data (card numbers, bank account details, billing addresses) flows through every transaction. IBM’s 2025 research found that customer PII was the most frequently compromised data type, involved in 53% of all breaches studied. At Payabli, we are committed to eliminating gaps in data protection entirely.

What’s next for data privacy in payments

This milestone strengthens our foundation, but it is not the finish line. Regulatory requirements, especially in fintech and digital payments, will continue to evolve. The EU has already proposed additional measures to streamline enforcement cooperation between data protection authorities, and new frameworks like the EU AI Act are introducing fresh governance expectations for platforms that use AI in data processing.

Meanwhile, in the US, roughly half of states with existing privacy statutes approved significant amendments in 2025 that either expanded coverage, refined key definitions, or enhanced enforcement tools. The compliance landscape is not slowing down. It is accelerating.

We will continue strengthening controls, expanding visibility, and deepening our data protection practices as our platform grows.

In payments, trust is the transaction. Strong data protection practices are essential to earning and maintaining that trust with customers and partners. That is the standard Payabli is committed to upholding.

Ready to work with a payments partner that takes data privacy seriously? Learn more about Payabli or visit our Trust Center to review our compliance documentation.